Is Africa ready for neobanks?

In October 2025, Wave, the Senegalese fintech that had disrupted mobile money across West Africa, created Wave Bank Africa S.A., a fully licensed commercial bank headquartered in Abidjan with CFA 20 billion in capital. A few months earlier, the Central Bank of Nigeria had upgraded Kuda, OPay and Moniepoint to national microfinance bank licences, lifting geographic restrictions on their operations.

African mobile operators are scaling, maturing, and converging toward banking. So, is Africa ready for neobanks? Not in terms of market demand, which is evident, but in terms of the conditions that allow a digital bank to sustain itself, serve the populations it claims to target, and do so without creating new risks for the financial system.

A market that narrows at the point of entry

According to the World Bank, 57% of the African population remains unbanked. Ninety percent of transactions in sub-Saharan Africa are conducted in cash. An estimated 60 million micro, small and medium enterprises are underfinanced. Mobile money has demonstrated that Africans will adopt digital financial services: $1.4 trillion flowed through mobile wallets on the continent in 2025. The demand is not in question. But the neobanks now emerging in Africa are not building from scratch. They are mobile money operators migrating toward banking. Wave had 21 million active users before creating Wave Bank Africa. OPay and PalmPay built their networks through payment services before seeking upgraded licences. The strategic logic is obvious. Mobile money margins are thin, and the path to sustainable revenue runs through banking, lending, deposit collection, and maturity transformation.[1]

The difficulty is that the client base built under a mobile money licence does not transfer to a banking licence. Mobile money in most African jurisdictions operates under tiered KYC: a basic account can be opened with a phone number and a name. This is what enabled rapid scaling. Banking requires full KYC compliance: formal identity documents, proof of address, and verification procedures that are significantly more demanding. When Wave transitions from EMI to bank, the 21 million users do not become 21 million banking clients. The base may shrink mechanically at the point of regulatory transition, because a proportion of mobile money users lack the documentation required to open a bank account. Ky, Rugemintwari and Sauviat (2021), using individual-level data from Burkina Faso, showed that mobile money and the formal banking system coexist as parallel circuits, not as a pipeline from one to the other. Grzybowski, Lindlacher and Mothobi (2023) found that the individuals most likely to be financially included are male, wealthier, more educated, and older. The addressable market for a neobank is real, but considerably narrower than the mobile money base from which it emerges.

Suppose, however, that regulators adapt and create lighter onboarding for digital banks. The problem shifts but does not disappear. A client acquired through a simplified digital process, without physical interaction, without the inertia of a branch relationship, is a structurally more volatile client. They arrived with a tap; they can leave with a tap. In traditional banking, deposit stability is supported by switching costs, geographic proximity, and relationship inertia. In a digital-only environment, these stabilising forces are absent. The deposit base may be large in number but fragile in character. This feature constrains exactly the activity that justifies the banking licence, which is maturity transformation.

The funding equation

To understand why neobank viability in Africa is not a matter of technology or product design but of financial structure, it is necessary to return to how banks make money. A bank collects deposits, which are short-term and can be withdrawn at any time, and lends them out at longer maturities, earning the margin between the two rates. This maturity transformation is the source of banking profit and is also the source of banking fragility, because it depends on the stability of the deposit base. If depositors withdraw faster than loans mature, the bank faces a liquidity crisis.

In sub-Saharan Africa, both channels through which banks fund themselves, deposits and market funding, are structurally constrained. Capital markets are shallow, access to international bond markets is costly and intermittent, the interbank market is limited, and the deposit base is narrow. The IMF has described the region’s situation as a “big funding squeeze.” In the WAEMU zone for example, bank credit to the economy remains below 30% of GDP, and 400 large companies absorb 30% of all bank credit, leaving the vast majority of the productive fabric underserved. Even well-established banks with decades of presence and branch networks struggle to mobilise sufficient stable funding.

For a neobank, this constraint is amplified. Without branches, deposit collection depends entirely on digital channels, and the deposits are inherently more volatile. Demirguc-Kunt and Huizinga (2010) have shown, in a broad cross-country study, that the structure of bank funding is a primary determinant of risk and return: banks that rely on less stable funding sources take on more risk and are more vulnerable to shocks. Khan, Scheule and Wu (2017) demonstrate that funding liquidity directly shapes bank risk-taking behaviour, with institutions facing tighter funding conditions more prone to excessive risk. These findings, established for traditional banks, apply with particular force to neobanks, where brand trust must be established from scratch, access to central bank refinancing is typically limited or unavailable, and the alternative source of funding, venture capital, has contracted sharply (global fintech investment fell approximately 40% from its 2021 peak). The result is that African neobanks face a funding environment that is more hostile than the one faced by traditional banks, precisely at the moment when they need stable, long-term funding most, because the clients they are bringing into the formal financial system for the first time require patient intermediation, not short-term transactional relationships.

TymeBank in South Africa is a perfect illustration. The bank holds a full licence from the SARB, has attracted 15 million customers, and recorded its first profitable month in December 2023. But its audited accounts for the year ending June 2025 show accumulated losses of 7.3 billion rand and a net loss of 218.8 million rand. The auditors flagged a material uncertainty regarding the company’s ability to continue as a going concern[2] beyond October 2026 without additional capital. The bank’s survival depends not on its deposit base but on the continued willingness of its shareholders to fund losses.

The contrast with European neobanks is instructive, though the lessons must be drawn carefully. Revolut, which began as an electronic money institution in the United Kingdom in 2015, secured a European banking licence in Lithuania in 2021 and now serves over 50 million customers globally at a $45 billion valuation. Its trajectory, from payment operator to licensed bank, mirrors that of Wave or OPay. But Revolut operates in conditions that are fundamentally different from the African context. It grew in a market with universal identification (national ID cards, passports, standardised address verification), meaning the KYC barrier that constrains African neobanks does not exist. It has access to deep European capital markets, to central bank facilities through its banking licence, and to a deposit insurance scheme (up to €100,000 per depositor). Crucially, Revolut is not bridging an inclusion gap: it is offering a cheaper, more flexible form of banking to customers who are already served by a mature financial system. Its funding base is stable because its customers are documented, embedded in regulated economies, and protected by institutional backstops that have been tested by crises.

Monzo in the United Kingdom reached 13 million customers and reported its first full-year profit in 2024 on revenue of £1.24 billion. Yet Monzo received a £21 million fine from the FCA in 2025 for inadequate anti-money laundering controls during its period of rapid growth, and Starling Bank was fined £29 million for similar failures the year before. In Germany, BaFin imposed a cap on N26’s customer onboarding in 2021 over compliance deficiencies, effectively throttling the neobank’s growth at a critical moment. Even in jurisdictions with deep capital markets, universal identification, and well-resourced regulators, the tension between scaling and compliance proved difficult to manage. The lesson is not that European neobanks have solved the problem. It is that they operate in an environment where the funding base, the identification infrastructure, and the regulatory backstops make the problem manageable. In Africa, these conditions are largely absent.

Why regulation matters more, not less

If the market narrows at entry and the funding base is fragile, the instinct might be to lighten regulation to give neobanks room to grow. This might backfire. Wagner (2007) demonstrated theoretically that while greater bank liquidity reduces the probability of bank runs, it can also lead banks to increase risk-taking. Prudential regulation exists for precise reasons: to protect depositors, to prevent excessive risk-taking, and to ensure that institutions collecting savings and extending credit can absorb losses without destabilising the broader system. These reasons apply with at least equal force to neobanks, and in some respects with greater force, because the risks they carry are different in nature from those of traditional banks.

The main question is whether the existing architecture fits what neobanks are, and whether the same barriers that constrain traditional banks will have the same coercive force on risk. The banking literature has shown that the introduction of requirements on liquidity or capital leads to measurable reductions in bank default risk. But they can also constrain profitability. For an established bank with diversified revenues, this trade-off is manageable. For a neobank that has not reached breakeven, the cost of holding liquid assets that generate little return or mobilising capital while building a customer base can be prohibitive.

To date, the prudential architecture facing neobanks in Africa has barely evolved. In South Africa, TymeBank operates under the same prudential rules as Standard Bank or FirstRand. Maximum credibility, maximum regulatory cost, on a structurally loss-making institution. In Nigeria, the CBN chose not to create a dedicated digital banking licence, instead upgrading fintechs within the existing microfinance bank tier, which limits their services but applies a lighter burden. In the WAEMU zone, Wave made the leap from EMI to fully licensed bank, accepting the full suite of prudential obligations. None of these approaches constitutes a framework designed for what neobanks actually are: institutions with elevated operational risk (technology failures, cybersecurity), concentration risk (narrow product range, limited customer segments), and deposit volatility, but typically less maturity transformation than traditional banks, at least in their early years.

Other jurisdictions have experimented with proportionate frameworks. Singapore’s Monetary Authority created a dedicated digital bank licensing framework in 2020, with tiered capital requirements that start lower than for traditional banks and increase as the institution scales. The framework explicitly recognises that digital banks carry different risks and should not be shoehorned into a framework designed for a different institutional form. Malaysia adopted a similar approach, issuing five digital banking licences in 2022 with a phased capital regime. In Brazil, Nubank, now the world’s largest neobank with over 100 million customers, grew under a regulatory environment that permitted lighter capitalisation in the early stages while progressively tightening requirements as the institution scaled.

The common thread is proportionality: regulation that is calibrated not to the institutional label (bank or non-bank) but to the actual risk profile at each stage of development. This does not mean lighter regulation. It means different regulation, one that recognises that the risks of a digital bank with 2 million customers and no loan book are not the same as those of a universal bank with 20 million customers and a century of maturity transformation. As the neobank grows, the regulatory requirements grow with it.

An institution Africa needs, on conditions it has not yet created

Neobanks will become a reality in Africa. They are needed, not merely to digitise payments, which mobile money has already achieved, but to ensure financial intermediation: the transformation of savings into credit, of deposits into productive investment. This is the function that the continent’s economies most lack, and it is the function that neither mobile money in its current form nor the traditional banking sector in its current reach can adequately provide. But for neobanks to fulfil this role, policymakers need to create the conditions for them to perform. That means addressing the identification infrastructure that determines who can be a client, the funding environment that determines whether a digital bank can sustain itself, and the regulatory architecture that determines what risks it can take and how it is supervised. Without these conditions, the most likely outcome is the emergence of digitised traditional banks, institutions that replicate the same narrow client base, the same funding constraints, and the same limited reach as their brick-and-mortar predecessors, but with a different set of operational risks.

The simplest path, already visible in some markets, is for mobile money operators to operate under the backing of a traditional bank, effectively becoming a digital branch. This is straightforward from a regulatory perspective and mirrors the model of several European neobanks that are subsidiaries of established banking groups. But it limits transformation: the neobank inherits the risk appetite, the capital constraints, and ultimately the strategic priorities of its parent. For Africa’s mobile money operators to genuinely transform into autonomous banks, or for new neobanks to be established from scratch, deeper work is required. That work should consider proportionate capital and liquidity frameworks calibrated to the digital model, interoperable digital identity systems that bridge the gap between mobile money KYC and banking KYC, and mechanisms to stabilise the deposit base of institutions that lack the branch networks and relationship inertia of traditional banks.

References

Demirguc-Kunt, A. & Huizinga, H. (2010). Bank activity and funding strategies: The impact on risk and returns. Journal of Financial Economics, 98(3), 626-650.

Grzybowski, L., Lindlacher, V. & Mothobi, O. (2023). Mobile money and financial inclusion in Sub-Saharan Africa. Information Economics and Policy, 65, 101064.

Khan, M.S., Scheule, H. & Wu, E. (2017). Funding liquidity and bank risk taking. Journal of Banking & Finance, 82, 203-216.

Ky, S.S., Rugemintwari, C. & Sauviat, A. (2021). Friends or Foes? Mobile money interaction with formal and informal finance. Telecommunications Policy, 45(1).

Wagner, W. (2007). The liquidity of bank assets and banking stability. Journal of Banking & Finance, 31(1), 121-139.

IMF (2023). Regional Economic Outlook: Sub-Saharan Africa. The Big Funding Squeeze.


[1] Maturity transformation: the core function of banking, which consists of collecting short-term deposits and using them to fund longer-term loans. This mismatch is the source of banking profit but also its principal vulnerability.

[2] Going concern: auditors’ assessment of whether a company can continue to operate for the foreseeable future. A going concern uncertainty is a formal warning that the company may not survive without additional capital.

The Two Kenyas: a booming economy, but for whom?

Stand on a rooftop in Nairobi at dusk and two Kenyas come into view. Above the skyline, glass towers glow over a city that runs the regional headquarters of Google, Microsoft and Visa and hosts the United Nations’ only global headquarters in the Global South, home to UNEP and UN-Habitat. In the street below, a trader folds up her stall and pays her supplier with a tap on a worn handset, one of the 76.7 million active SIM lines registered for a population of about 56 million, a mobile penetration above 145 percent,1 on a market that M-Pesa dominates, with 47.7 million active mobile-money accounts and a 91 percent share.2 She is also one of the more than 8 in 10 Kenyans whose work is informal, with no contract and no protection.3 Same skyline, two worlds.

The figures behind that skyline are big. In 2025 Kenya quietly passed a milestone it had chased for a decade: with output of about US$136 billion in 2025 (KES 17.58 trillion), it overtook Ethiopia, now about US$109 billion, to become the largest economy in East Africa.4 It has topped Africa’s rankings for startup capital in recent years, pulling close to $1 billion to its founders in a single year.5 Renewables supplied 80.2 percent of its electricity in the year to June 2025, geothermal steam from the Rift Valley being the single largest source at 39.5 percent.6 Its diaspora wired home US$5.04 billion in 2025, more hard currency than tea, tourism or any single export earns.7 And it is young in a hurry: 3 in 4 Kenyans are under 35.8 None of this is promise. It is already built.

And yet. The largest economy in the region is also the slowest-growing of its major neighbours.9 It is courted by global investors as a rising star, and 39.8 percent of its citizens still live below the national poverty line.10 And in June 2024 a generation of young Kenyans, organised on TikTok and X with no leader and no party, marched on their own Parliament and briefly stormed the chamber rather than pay for the government’s budget gap. This article is about the distance that protest exposed: the gap between how Kenya’s growth looks from the outside and what it is actually made of on the inside.

That gap is the single most important thing to understand about the country today, whether you are a Kenyan worker, a finance minister in Nairobi, or an investor in Lagos, London or Shanghai weighing a continental bet. To make sense of it we will do two things at once: take the full measure of what is remarkable about Kenya’s rise, and then open the engine of that rise with four simple tools, each in plain language, to see what is really driving it. The conclusion is not that Kenya is failing, far from it: Kenya has won the easy contest, size, while the one that decides a country’s future, whether the boom reaches its people, is still wide open.

The Kenya the world has started to notice

Begin with the achievement, because it is impressive, and because Kenya did not merely grow; it invented things the rest of the world now copies. Mobile money was born here in 2007, and today a Kenyan pays a market trader, a hospital, a landlord or a solar-power supplier with a few taps on the most basic handset, with M-Pesa alone carrying more than 9 in 10 of them. A country much of the world still pictures as poor leapfrogged the bank branch and the chequebook altogether and built, on the phone, a financial system that richer nations are still trying to imitate.

That digital edge is now drawing the world’s biggest names. Microsoft and the Emirati group G42 are building a data centre worth around $1 billion, run on Kenya’s geothermal power, the largest private digital investment in the country’s history.11 The reach is more tangible than servers, too: the roses in a European supermarket bouquet were most likely cut the day before near Lake Naivasha and flown overnight to the auctions of Amsterdam, for Kenya is one of the world’s leading flower exporters.12 The emergence is no slogan: it is broad-based, and it is precisely why the stakes of the rest of this article are so high.

The rise is genuine. So is the crack beneath it.

Now look underneath. Real growth has slowed for three straight years, from 5.7 percent in 2023 to 4.7 percent in 2024 and 4.6 percent in 2025, the weakest pace since the pandemic.13 Over the same year East Africa as a whole grew by 6.4%, the fastest of any African region.14 Put simply, the biggest economy in the neighbourhood is now growing more slowly than the neighbourhood; Ethiopia, Rwanda and Uganda are all pulling ahead on pace.

This is not a crisis, and it would be wrong to read it as one. The slowdown came wrapped in real macroeconomic stability: a shilling holding near 129 to the dollar and official reserves of US$13.24 billion in June 2026, 5.6 months of import cover. Stability, though, is no longer the whole story: inflation, which averaged 3.8 percent in 2025, had climbed to 5.6 percent by April 2026, rising on fuel, food and transport but still within the Central Bank’s 2.5 to 7.5 percent band.15 Where Ethiopia reached an IMF rescue only after a forced devaluation, Kenya kept its money convertible and its capital account open throughout. The country has traded a little speed for a great deal of predictability, exactly what long-term investors prize. The honest question is not whether Kenya is stable. It plainly is. It is what kind of growth that stability is protecting, and that is where the celebration has to give way to the diagnosis.
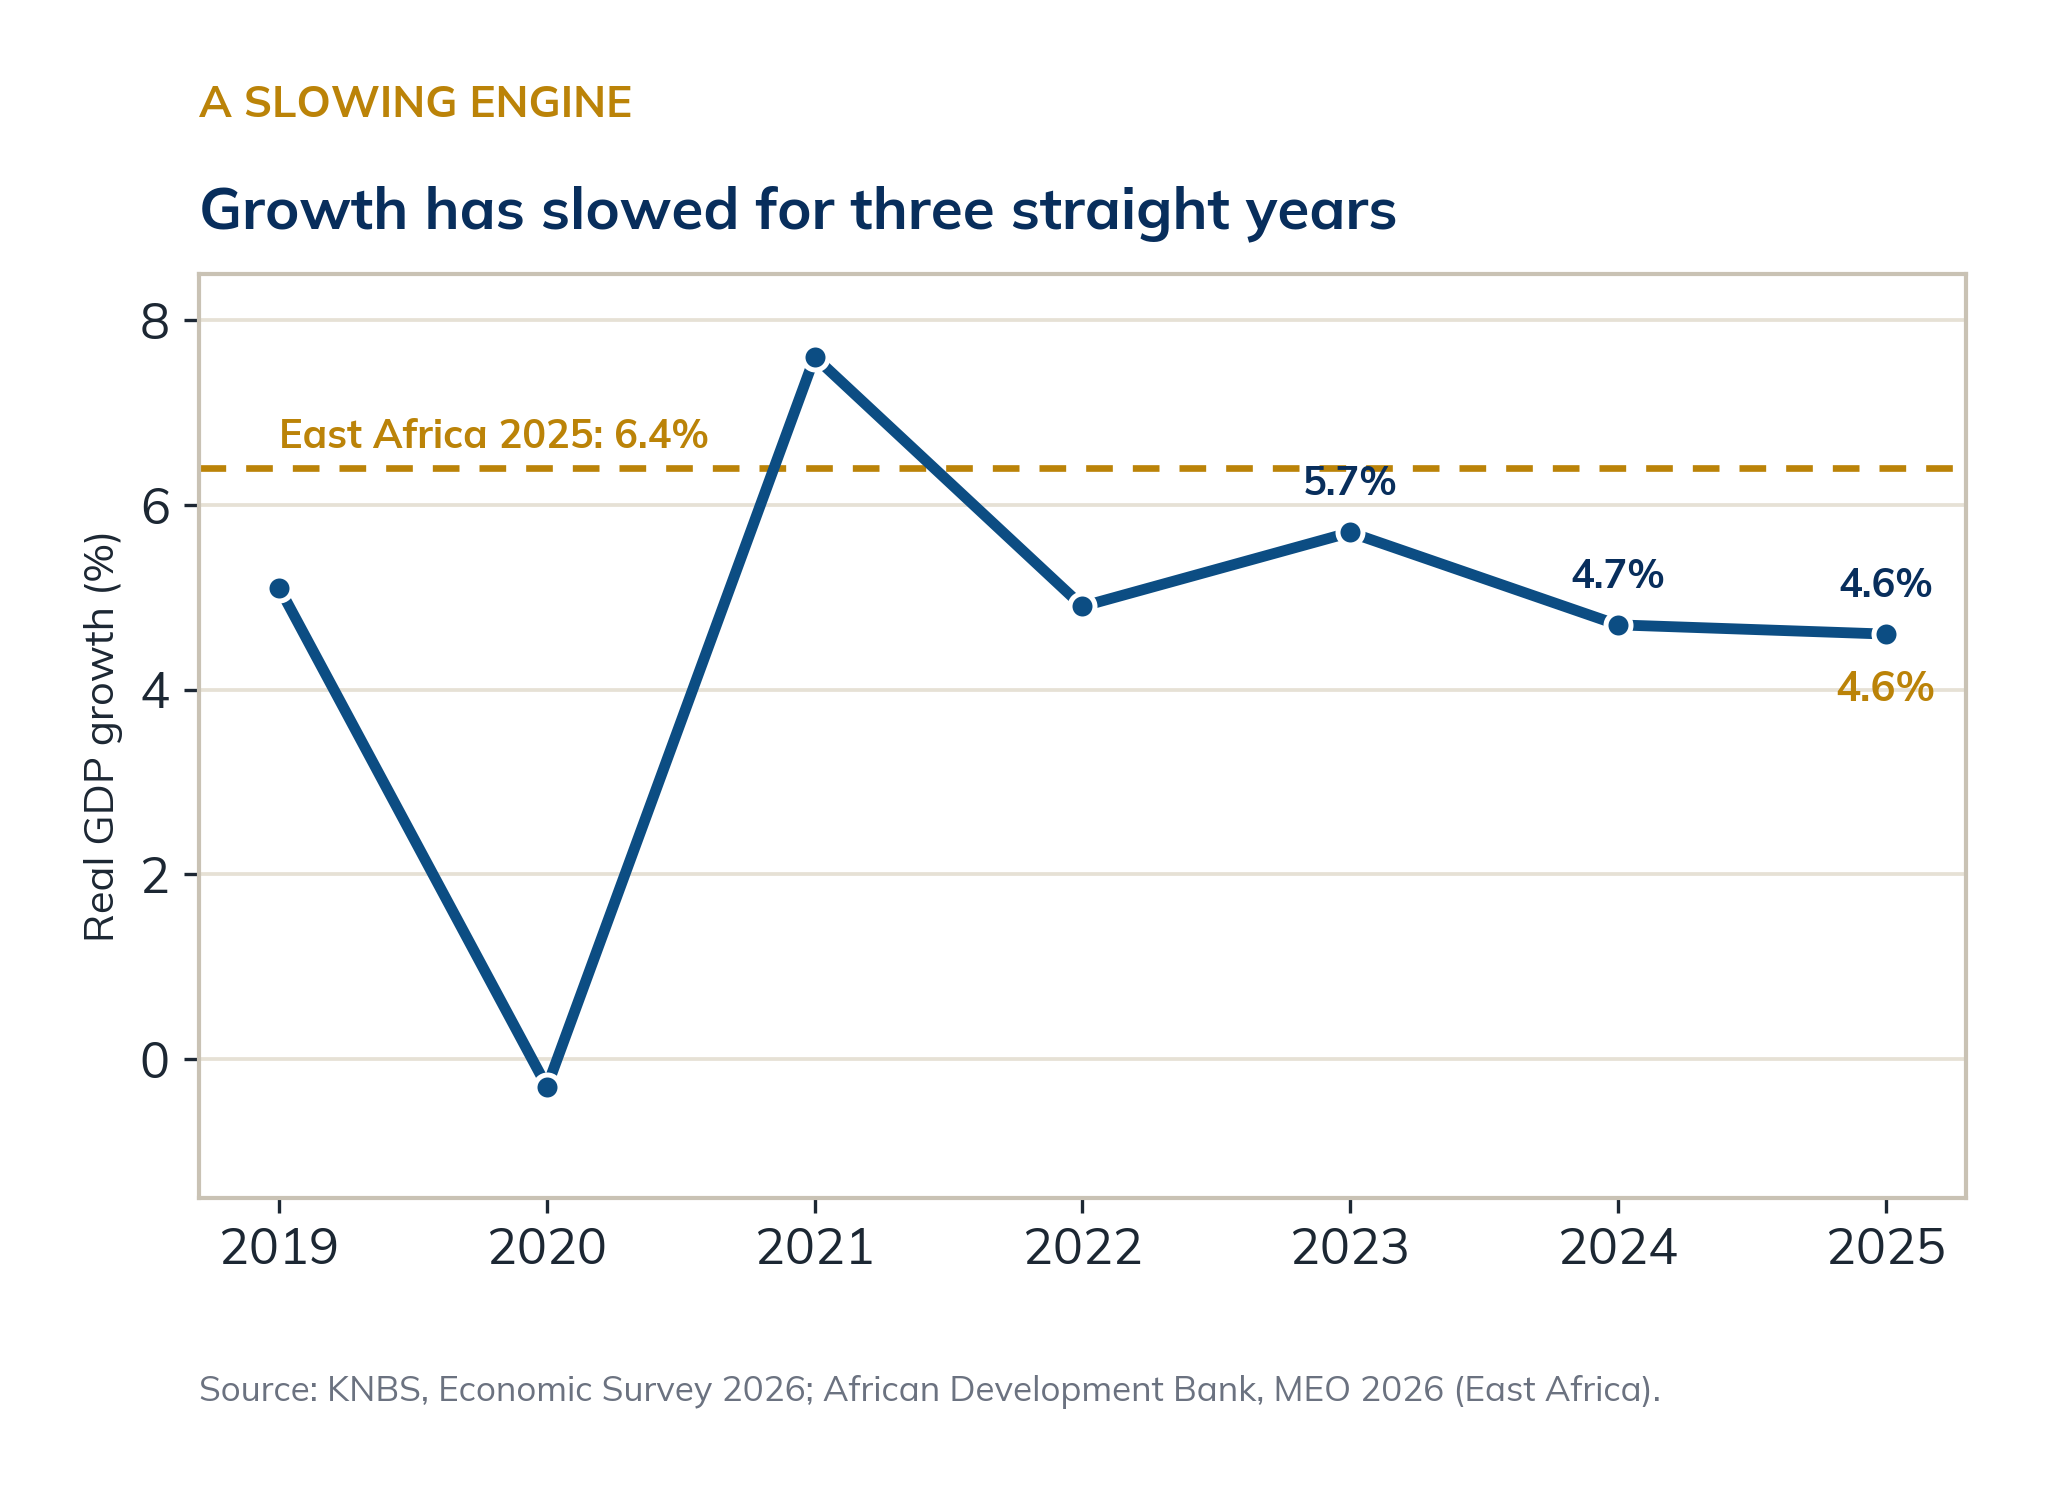
Real GDP growth, Kenya 2019 to 2025, against the East African benchmark for 2025.

Real GDP growth, Kenya 2019 to 2025, against the East African benchmark for 2025.

To judge an economy, ask what its growth is made of

Economists open the engine with a method called growth accounting. The idea is simple. An economy can grow for three reasons: it uses more machines, buildings and roads (more capital); it puts more people to work (more labour); or it uses what it already has more cleverly (higher productivity). That last ingredient, the efficiency with which inputs combine, is the magic one, because it is the only source of growth that never runs out.16 That priority is a choice of school, not a neutral fact: productivity is measured as the residual left once capital and labour are counted, and the residual shifts with the assumptions made about the capital stock and its depreciation. The accumulationist reading of the East Asian miracle, Young and Krugman, saw mostly perspiration, more capital and labour, where the productivity-first tradition of Solow, and of Easterly and Levine, saw inspiration. This article takes the productivity-first view with that caveat in plain sight.

METHODOLOGICAL BOX · WHERE GROWTH COMES FROM

gY = α · gK + (1 − α) · gL + gA

In words: growth (gY) equals the contribution of more capital (gK), plus more labour (gL), plus the productivity gain (gA) from using both better. A country that grows only by piling on capital and workers, with little productivity gain, is running on brute force, and brute force meets diminishing returns.

Applied to Kenya, the verdict from the research is consistent. Growth-accounting studies, from analyses of the 1970s and 1980s to recent work, find that most of Kenya’s output growth is explained simply by adding inputs, more capital and more workers, while total factor productivity, the efficiency term, has been weak, volatile and in several periods outright negative.17 In one well-known result, productivity made no net contribution to growth between 1970 and 1985; later studies confirm a thin and unstable productivity record, even as a few argue it has lately begun to improve. The conclusion holds: Kenya grows mainly by accumulation, not by efficiency, and accumulation without rising productivity eventually tires.

Table 1. The sources of Kenya’s growth: what the evidence shows.

Source of growth Role in Kenya’s growth What the studies find
Capital accumulation Primary driver Most output growth explained by a rising capital stock
Labour Major driver Labour-surplus economy; employment a large contributor
Total factor productivity (efficiency) Weak and volatile Little or no contribution in many periods, negative in several

Directional summary of growth-accounting studies on Kenya (Solow and Cobb-Douglas framework, 1970s to recent), with AfDB and KIPPRA productivity analyses. The recurring finding: growth driven by inputs, with total factor productivity weak, volatile and in several periods negative.

A country grows only as fast as it invests, and Kenya invests too little

If growth runs on accumulation, how much a country invests sets its speed limit. The oldest rule in development economics says it in one line.

METHODOLOGICAL BOX · THE SPEED LIMIT

g ≈ s ÷ v

Sustainable growth (g) is roughly the investment rate (s, the share of income put into new capital each year) divided by how much investment it takes to produce 1 extra unit of output (v). You grow faster by investing more, or by investing more wisely, or both. This is a heuristic, a first approximation rather than an exact law; what matters is the direction, not the decimal.

On the first lever Kenya is structurally short of fuel. It invests 17.7 percent of its income each year (gross fixed capital formation, 2024), below the sub-Saharan average and far below the 30 to 42 percent that financed South Korea, Vietnam and China at their take-off.18 The arithmetic here is descriptive, not predictive: with an incremental capital-output ratio of about 3.8, itself read off recent data rather than assumed, a 17.7 percent investment rate maps onto growth of roughly 4.7 percent. That mapping rests on a strong and questionable assumption, that the capital-output ratio holds steady; if Kenya simply allocated capital better, the same 17.7 percent could sustain faster growth, so the figure marks current efficiency, not a fixed ceiling. The value of the exercise is not the decimal but the bridge it reveals between the two frameworks. The ratio v is exactly where productivity enters: a more efficient economy turns the same investment into more output, a lower v and a higher ceiling. Raising productivity and raising investment are therefore not rival strategies but one project seen twice, getting more growth out of each shilling put to work. Kenya is short on both counts at once.

Read the same identity backwards and it turns into a comparative lens, one that isolates the part of growth lying between brute accumulation and pure productivity. Rearranged, v is simply s divided by g: an economy’s incremental capital-output ratio is its investment rate over its growth rate. Kenya’s comes to about 3.8, meaning it currently takes close to four units of investment to add one of output. The figure is ordinary; its use is comparison. An economy investing the same share but running a lower ratio grows faster, and that ratio is where infrastructure, skills, project selection and the choice between a shopping mall and a factory all register. It is the lever Kenya can pull without first raising its savings rate or staging a productivity revolution: the same 17.7 percent, allocated better, would buy more growth. This efficiency-of-investment channel, short of total factor productivity but well beyond mere accumulation, is the one the rest of this series follows most closely.

The shortfall, moreover, is one of saving before it is one of channelling. Kenyans save only about 13 percent of national income, well short of what their investment rate requires and far below the world average of roughly a quarter, so the difference is made up by borrowing from abroad.19 The instinct to save is nonetheless deep and visible: the regulated SACCO movement alone holds around KES 1.08 trillion in assets, close to 6 percent of GDP, for some 7.4 million members, and the informal chamas mobilise more still. The capital exists in the society. What is missing is the formal, investable channel, and a national savings base, to turn it into the factories, ports and power lines that raise the ceiling. It is worth adding that the economies Kenya is measured against did not simply decide to invest more: South Korea, and later Vietnam and China, mobilised savings through financial repression and state-directed credit, captive institutions that funnelled domestic savings into industry. Kenya, with a liberalised financial sector and an open capital account, cannot copy that machinery, which is part of why the comparison is a benchmark of scale rather than a template.20
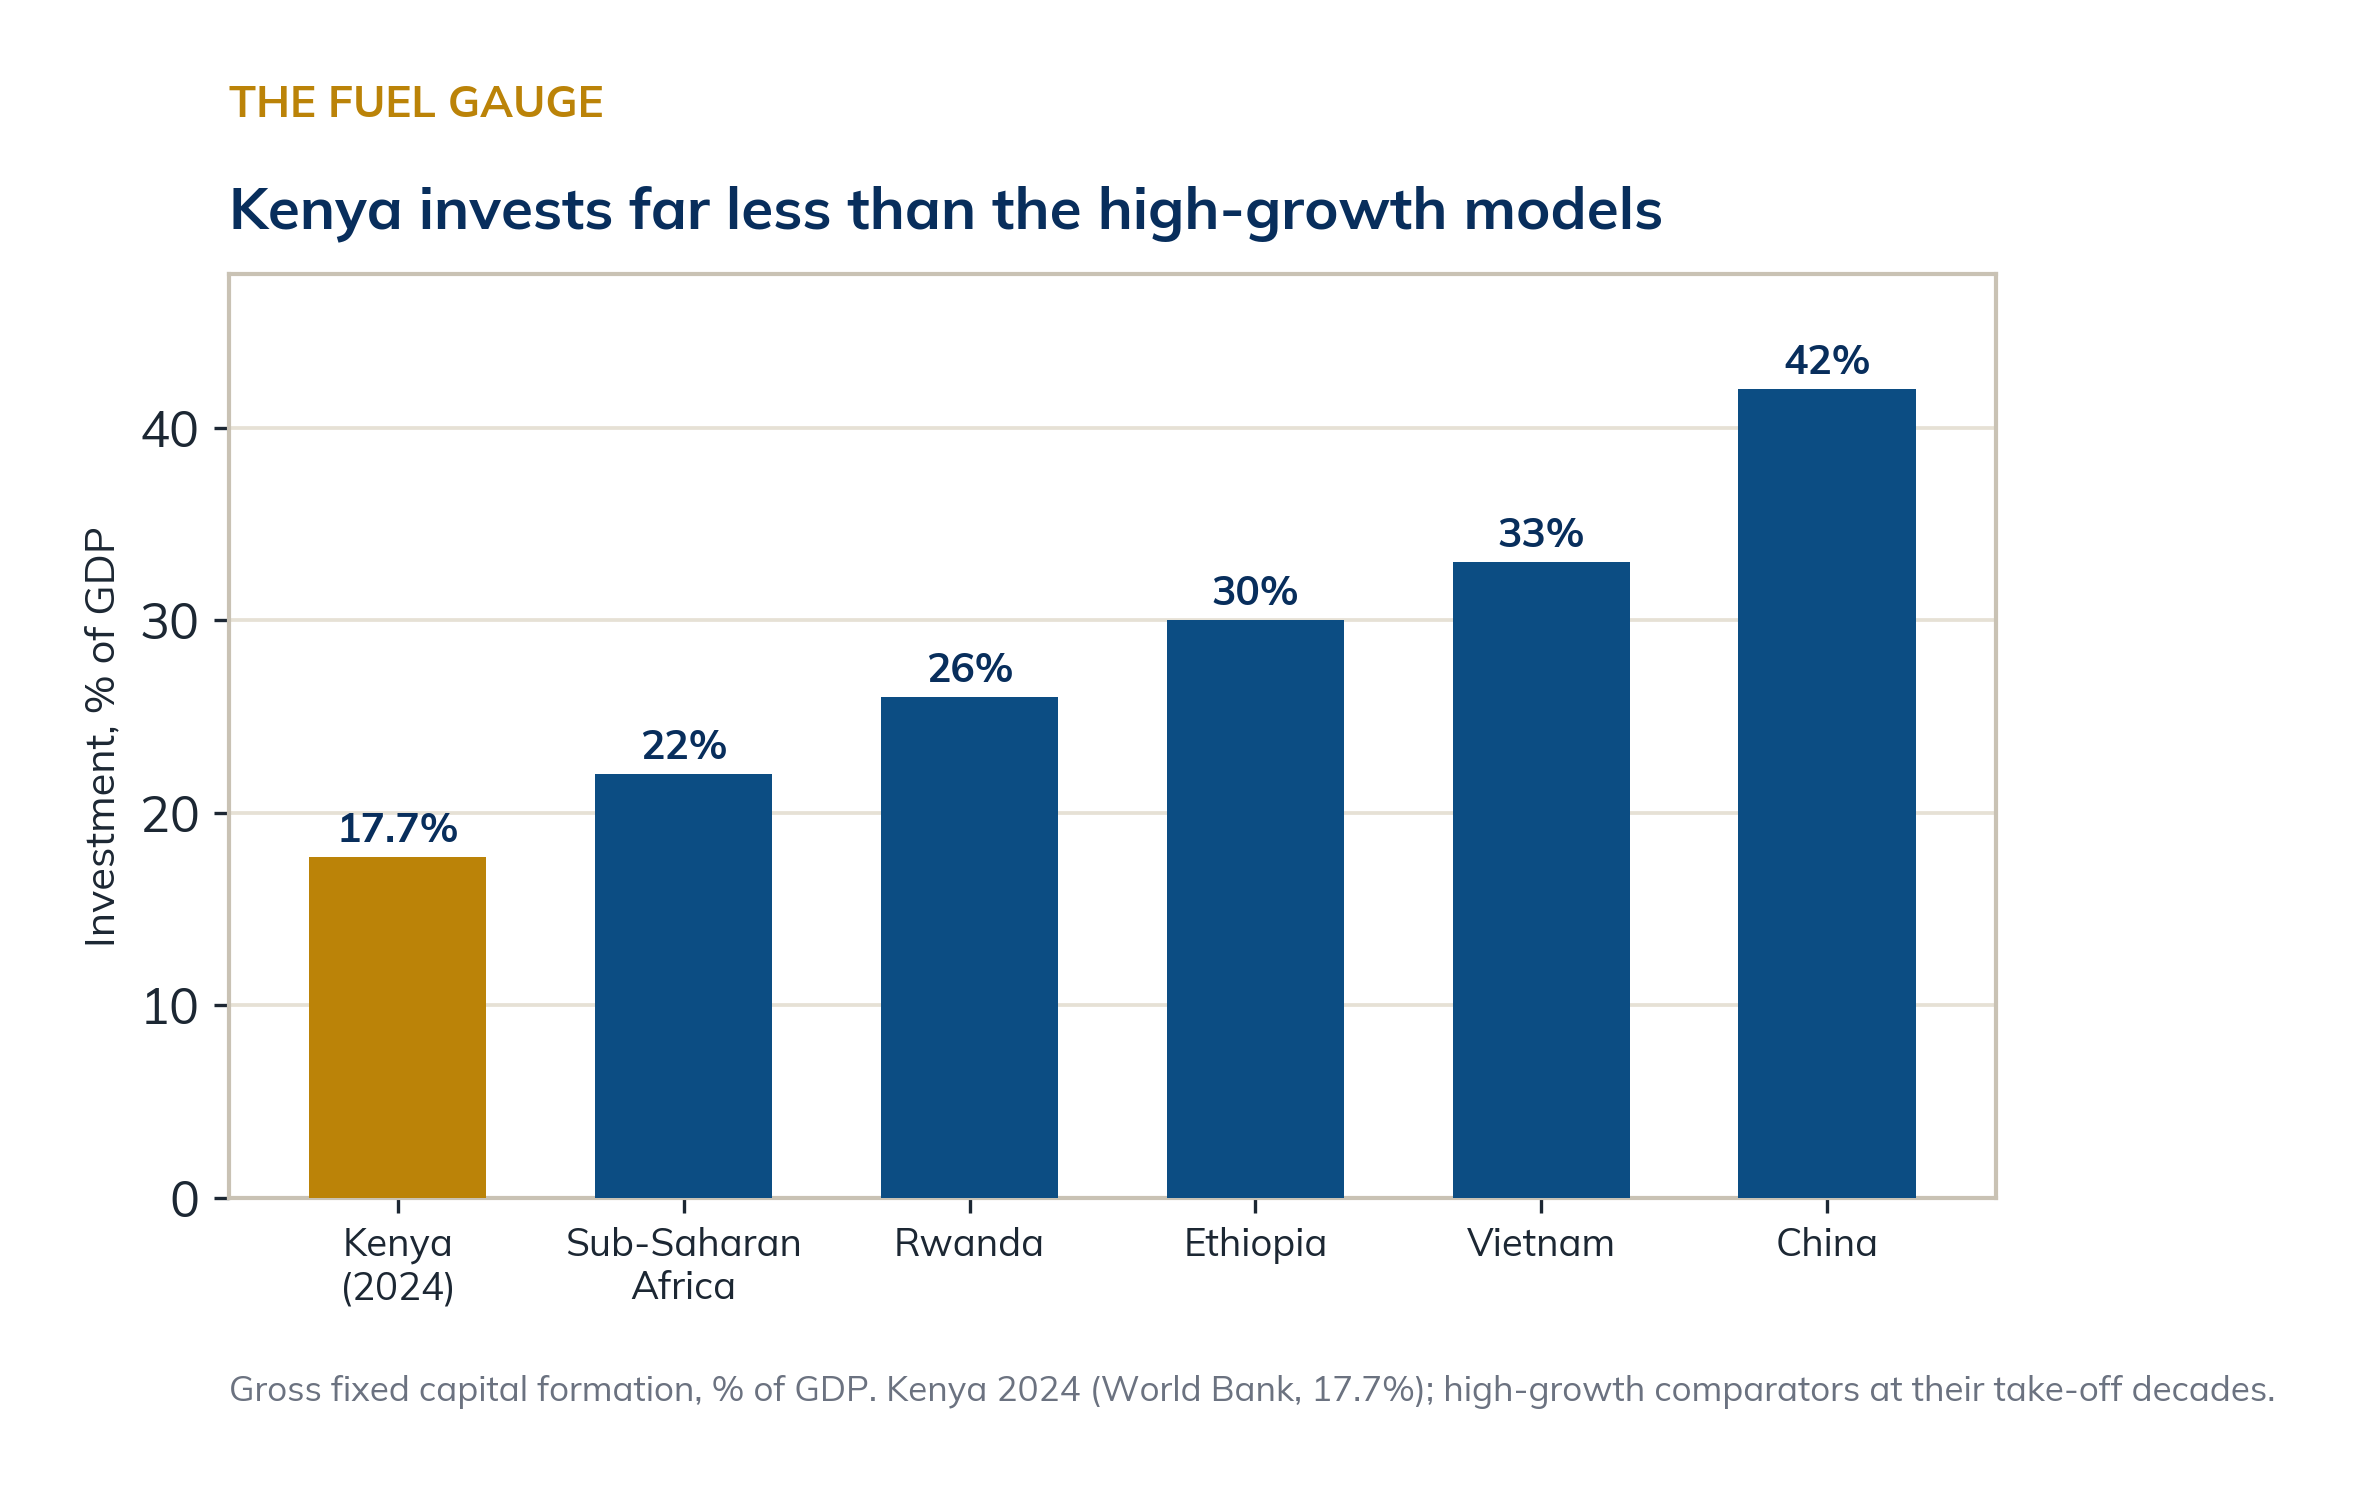
How much each economy invests: Kenya against the high-growth models.

How much each economy invests: Kenya against the high-growth models.

There is also a reason the state cannot make up the difference, and it sits in plain view in the budget. Servicing the public debt now absorbs about 69 percent of government revenue, more than double the level the IMF treats as prudent, and interest payments alone have climbed from 18 to 25 percent of all public spending in four years.21 Recurrent commitments, debt service and the public wage bill together take roughly 73 percent of the budget, leaving a thin margin for the roads, power, ports and clinics that public investment is meant to build. The debt does not only raise the risk of distress; it crowds out the very capital spending that would lift the growth ceiling. The fiscal arithmetic and the growth arithmetic turn out to be the same arithmetic.

The second lever, investing wisely, is where the services tilt both helps and hurts. Money put into services and real estate often pays off quickly, which flatters the short-run numbers, but it builds less of the productive, export-capable capacity that compounds over decades. A shopping mall raises output once; a factory or a port keeps raising it. Kenya’s task is double: to invest more, and to steer that investment toward the tradable, productive sectors that lift productivity rather than the consumption-serving activities that merely circulate it.

The economy is creating jobs. It is not creating the right ones.

Nowhere does the quality of growth show more starkly than in the jobs it makes. The link is one ratio.

METHODOLOGICAL BOX · HOW MUCH WORK GROWTH CREATES

ε = (ΔL ÷ L) ÷ (ΔY ÷ Y)

The employment elasticity: the percentage rise in jobs for each 1% of growth. Near 1, growth is rich in jobs; near 0, it leaves work behind. What matters most is not the headcount but the elasticity of good, formal, productive jobs.

In 2025 Kenya created 822,100 jobs, a fine headline.22 But the composition empties the comfort out of it. About 716,800 of them, 87.2 percent, were informal: street vending, casual labour, small unregistered trades with no contract, no protection, low productivity. Formal, wage-paying employment, the kind that pays tax, offers security and raises living standards, grew by only about 105,000. Against demography it is brutal: with around 1 million young people entering the labour market every year, only about 105,000 found formal work: barely one in ten of the new entrants, and fewer than one in eight even of the jobs actually created. Wage employment is just 15.3 percent of the 21.6 million recorded jobs, and the KNBS real-wage index has slipped to 85.84 (2009 = 100), so the average worker’s pay buys less than it did over a decade ago. A young graduate in Nairobi today is statistically more likely to end up hawking goods in traffic than to find a salaried post, and she knows it. None of this disparages the informal economy: Kenya’s jua kali is inventive, resilient and the backbone of daily life. The problem is not that it exists, but that nothing pulls it upward, into firms that can raise productivity, pay more and grow. Walk through Gikomba market at first light, or watch the boda boda riders thread the morning traffic, and you are looking at the real labour market: millions of micro-entrepreneurs improvising a living the formal economy never built for them.
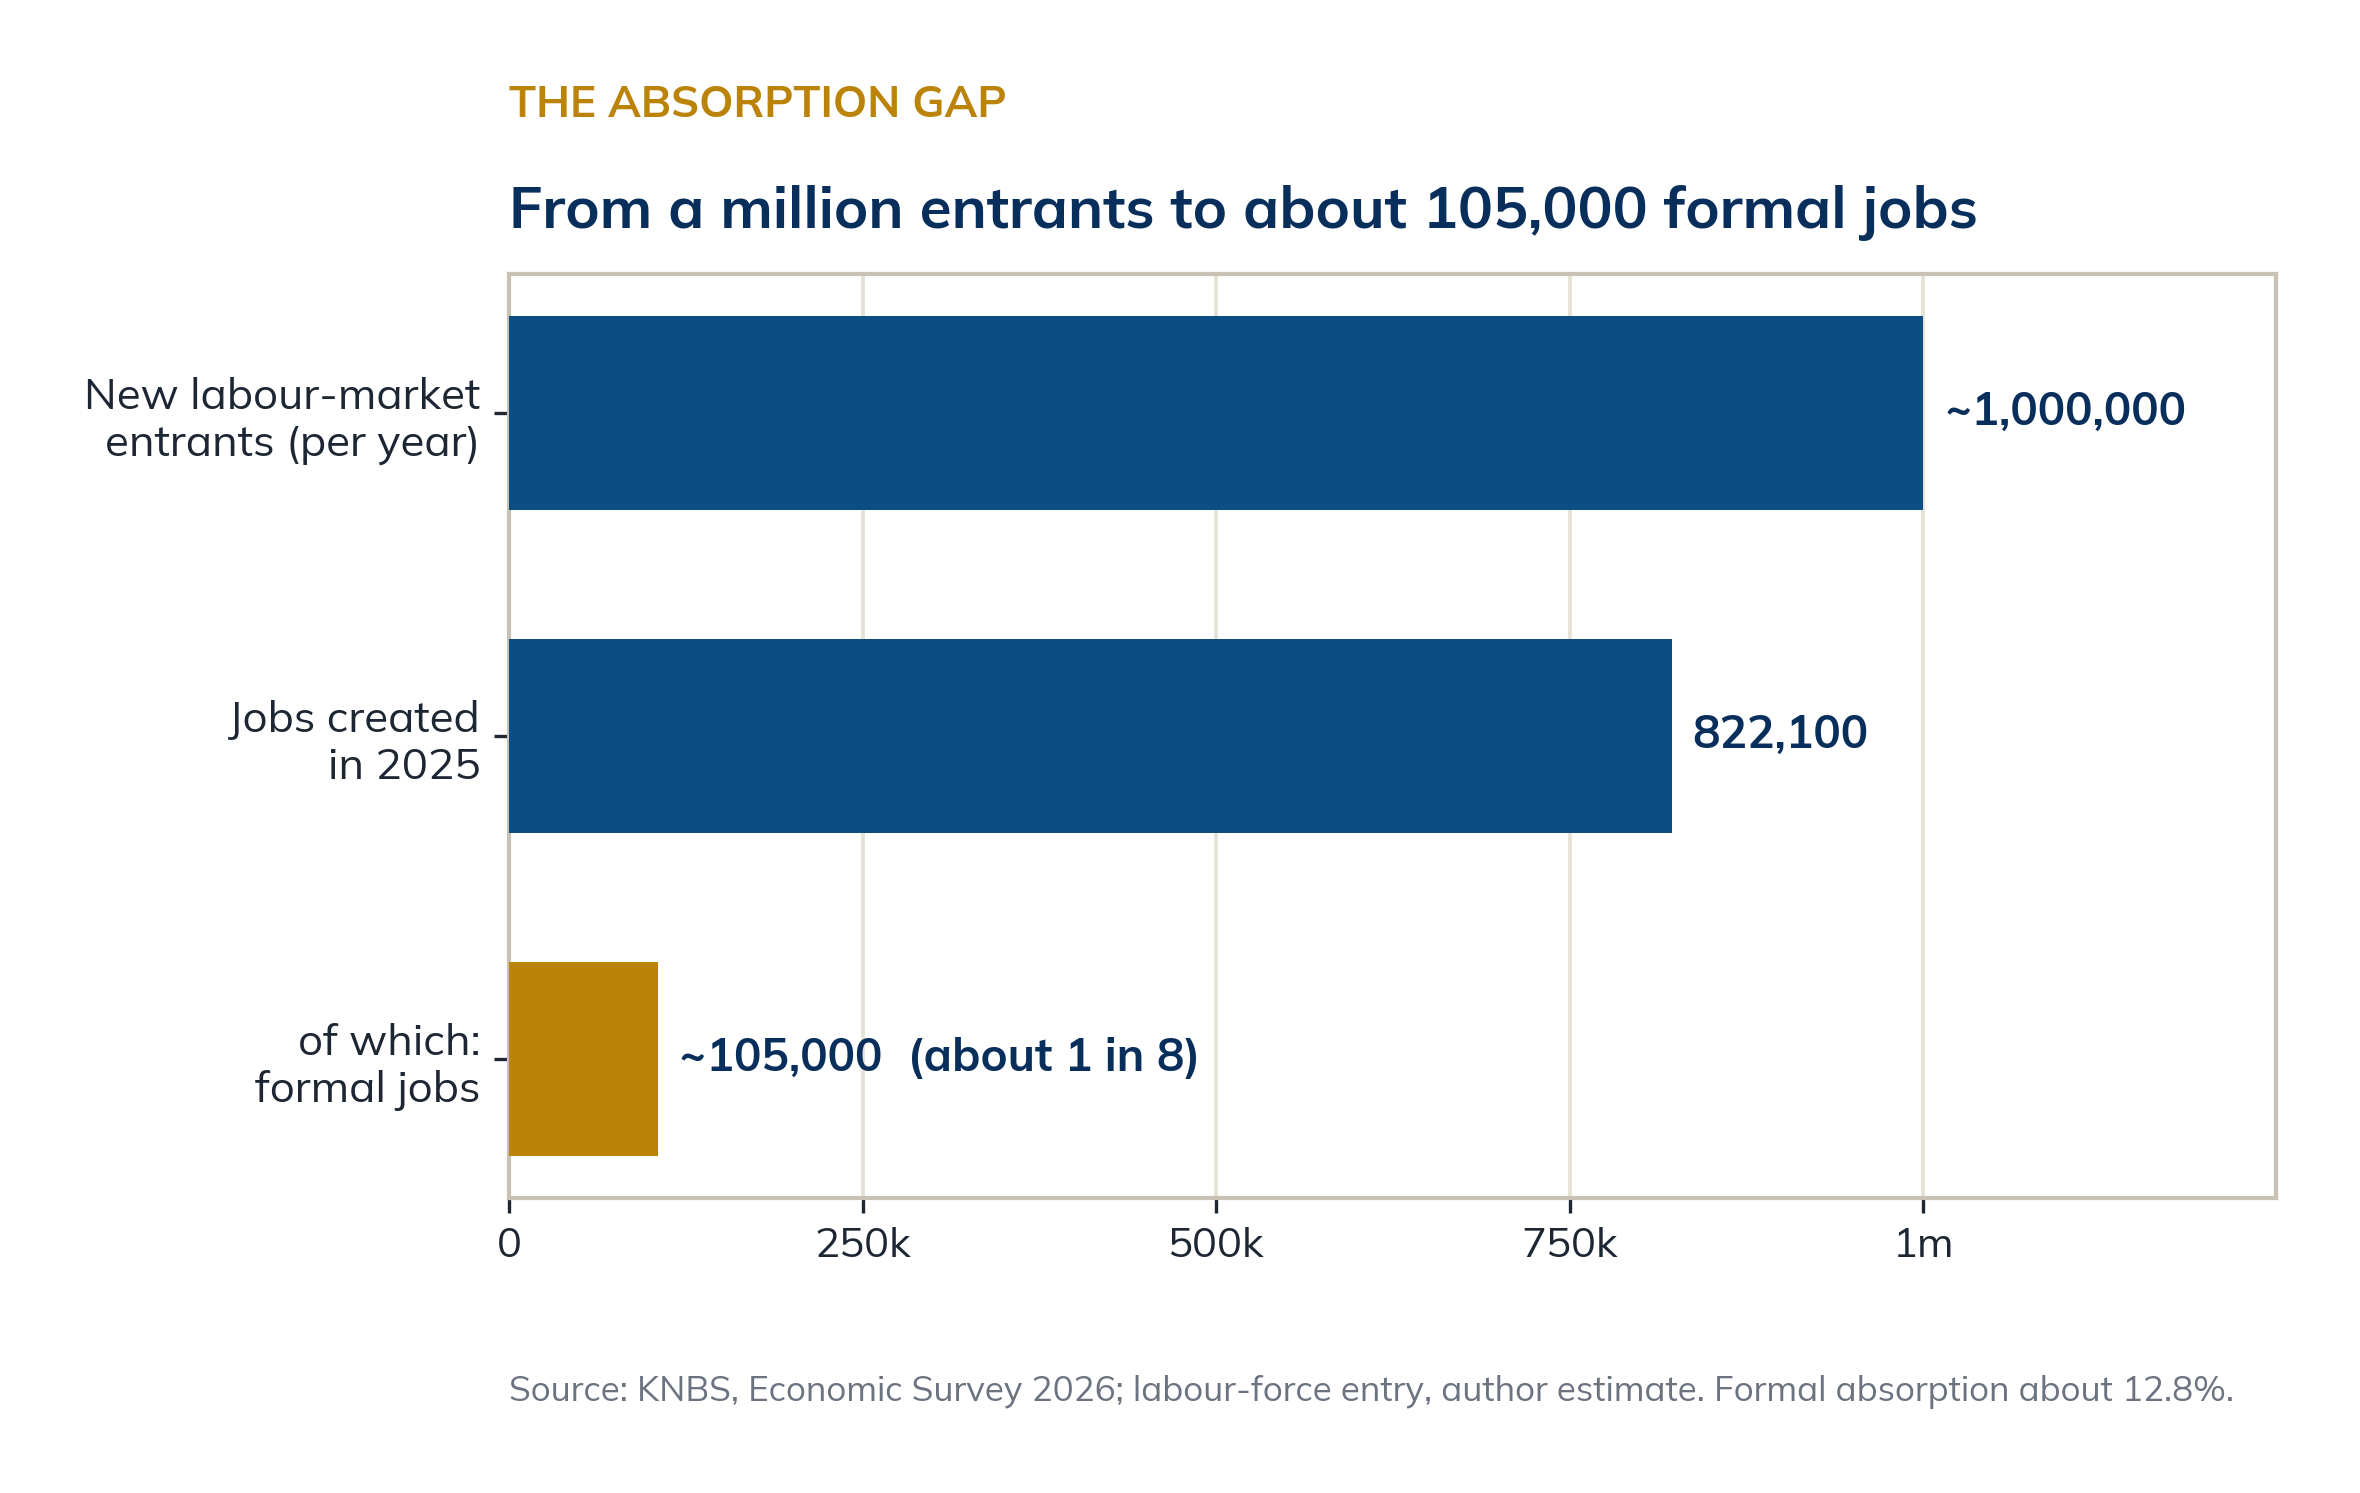
Kenya's jobs funnel, 2025: from roughly a million entrants to about 105,000 formal jobs.

Kenya’s jobs funnel, 2025: from roughly a million entrants to about 105,000 formal jobs.

This is the heart of the matter. Growth that funnels new workers into low-productivity informal activity can look healthy in the national accounts while delivering little to families and even less to the state, which can tax only the formal base. Kenya does not need to grow faster so much as it needs its growth to mean more, to pull people up the ladder from informal hustle into formal, productive work. That, not the growth rate, is the test the next decade will set, and it is a deeply human one.

The factories that were promised never arrived

Why is the supply of good jobs so thin? Because the sector that historically manufactured them, literally, has been shrinking. Manufacturing accounts for just 7.1 percent of GDP, well below the 15 percent Vision 2030 set as its target, and in 2025 it grew only 2 percent, slower than the economy as a whole, so its share keeps slipping.23 The economist Dani Rodrik named this pattern premature deindustrialisation, the fate of economies whose factories peak early, at low incomes and at a fraction of the weight East Asia reached. South Korea and Taiwan let manufacturing climb past 25% of their economies before it receded; Vietnam and Bangladesh built booms by plugging into global supply chains. Kenya is shedding industrial weight before it ever truly industrialised. Agriculture, which still makes up 23.2 percent of GDP and a far larger share of jobs, remains mostly rain-fed, smallholder and low-value, with the processing that would lift its value largely missing. And because manufacturing and agro-industry are the escalator that carries workers from informal to formal jobs, an escalator with too few steps leaves most standing where they began.

The question that matters, though, is not whether Kenya should have more factories but whether it can make things the world will buy, and there part of the constraint is external. Global manufacturing has fragmented into value chains dominated by established Asian producers, Vietnam and Bangladesh among them, competing on a scale and logistics that a firm shipping through Mombasa, with its port delays, high inland transport costs and steep energy prices in several subsectors, struggles to match.24 Seen honestly, Kenya’s revealed strengths lie elsewhere. It is the world’s leading exporter of black tea, a major supplier of cut flowers to the European market and a competitive exporter of coffee and horticulture; its one real manufacturing-export success, apparel, was built almost entirely on the duty-free access of AGOA, which lifted Kenyan garment exports to the United States from about US$55 million in 2001 to US$603 million by 2022, roughly two-thirds of all it sold there, and which lapsed in 2025.25 The implication is not a generic call for factories but a sharper one. Kenya’s realistic industrial path runs through agro-processing, turning the tea, coffee, horticulture and dairy it already grows competitively into higher-value exports; through selective niches where it can meet world standards; and through the regional EAC and COMESA markets that already absorb much of its manufactures. The door to mass low-wage manufacturing that East Asia walked through is narrower now, and Kenya has to industrialise on the comparative advantages it actually holds.

Kenya is running a model built for a different country

Line Kenya up against the great growth stories of the past half-century and its identity comes into focus. The East Asian tigers grew on very high investment, manufactured exports and fast productivity catch-up. Vietnam and China grew by drawing in foreign investment that pulled local firms into global production. Ethiopia grew on state-led public investment driving farms toward factories, at the cost lately of a currency crisis. Mauritius prospered on finance, tourism and offshore services. Kenya fits none cleanly; it most resembles a services-and-consumption economy, cushioned by remittances and a deep home market, with a low investment rate and a receding industrial base.

Table 2. Five growth models, and where Kenya sits.

Model What drives it Investment Example
Export-industrial Manufactured exports, high savings 35-40% South Korea, Taiwan
Value-chain / FDI Foreign investment into global supply chains 30-42% Vietnam, China
State-led investment Public investment, farms to factories 28-35% Ethiopia
Services hub Finance, tech, tourism, offshore services moderate Mauritius
Services-consumption Home services and consumption, remittances 17.7% Kenya

Typology by the author; investment rates from World Bank data (approximate, recent years).

The comparison is a diagnosis, not a verdict. A services-led model is not inferior in principle; Mauritius built real prosperity on it. But Mauritius did so with strong institutions, high incomes and a small, ageing population, turning services into high value per worker. Kenya runs a services-led model at low income, with a young and fast-growing workforce that services alone cannot absorb into formal jobs, and an investment rate too low to lift the productivity that would raise wages. Kenya is, in short, running a model built for a richer, older, smaller country than the one it actually is. The answer is not to copy Seoul or Hanoi: those paths belong to other histories and other states. It is to build a Kenyan model, services strength fused with a revived productive and agro-industrial base, financed first by Kenyan savings, and fitted to a young, rural-and-urban, county-devolved society.

This is why the boom barely reaches the poor

A last tool asks who actually receives the growth.

METHODOLOGICAL BOX · WHO GETS THE GROWTH

%ΔPoverty = η · %ΔIncome

The fall in poverty equals income growth multiplied by η, the growth elasticity of poverty. The point: η is not fixed. Growth cuts poverty far less in an unequal society, because the gains pile up with those already above the line.

METHODOLOGICAL BOX · GROWTH OR DISTRIBUTION

ΔP = G + D + R

The change in poverty splits into a growth component (G), the effect of a rising average income at an unchanged distribution; a redistribution component (D), the effect of a changing distribution at an unchanged average; and a residual (R). Inclusive growth is simply growth in which G and D both push poverty down.

Read through that lens, Kenya’s record is legible. For two decades poverty fell on the strength of both components: average income rose, and the distribution narrowed, the Gini sliding from 46.5 in 2005 to 38.5 today. But each has lost force. The redistribution component is largely spent, since a Gini already moderate has little room left to fall, while the growth component, as the next lines show, has been weakened by the sectors that produced it.26 Future poverty reduction has to come from a growth component made stronger, growth that is labour-intensive, linked and spatially spread, rather than from squeezing an inequality that is no longer the binding problem. That is the analytical heart of inclusive growth for Kenya.

What keeps that elasticity low in Kenya is less the level of inequality, moderate by world standards and below Ghana or South Africa, than the composition of the growth itself. The sectors driving the expansion, financial and insurance services up 6.5 percent in 2025 and information and communication up 4.8 percent, alongside real estate, hospitality and mining, are capital and skill intensive, with thin links up and down to the mass of informal and rural workers. The sectors that actually employ Kenyans lag: agriculture, 23.2 percent of GDP but growing 3.1 percent, and manufacturing, the classic bridge from informal to formal work, growing 2 percent and now only 7.1 percent of output. Growth concentrated in high-productivity, low-linkage activity lifts the aggregate while bypassing the labour-intensive sectors that would carry it to the poor; the elasticity is low by construction, not merely by the Gini.27 The composition of growth, the cross-country evidence finds, matters for poverty as much as its pace: labour-intensive sectors such as agriculture and construction cut poverty more per point of growth than capital-intensive finance or extraction.28 L’Afrique des Idées’ own work on inclusive growth makes the same point at continental scale: where growth is broad and linked across sectors, poverty falls; where it is narrow, it does not.29
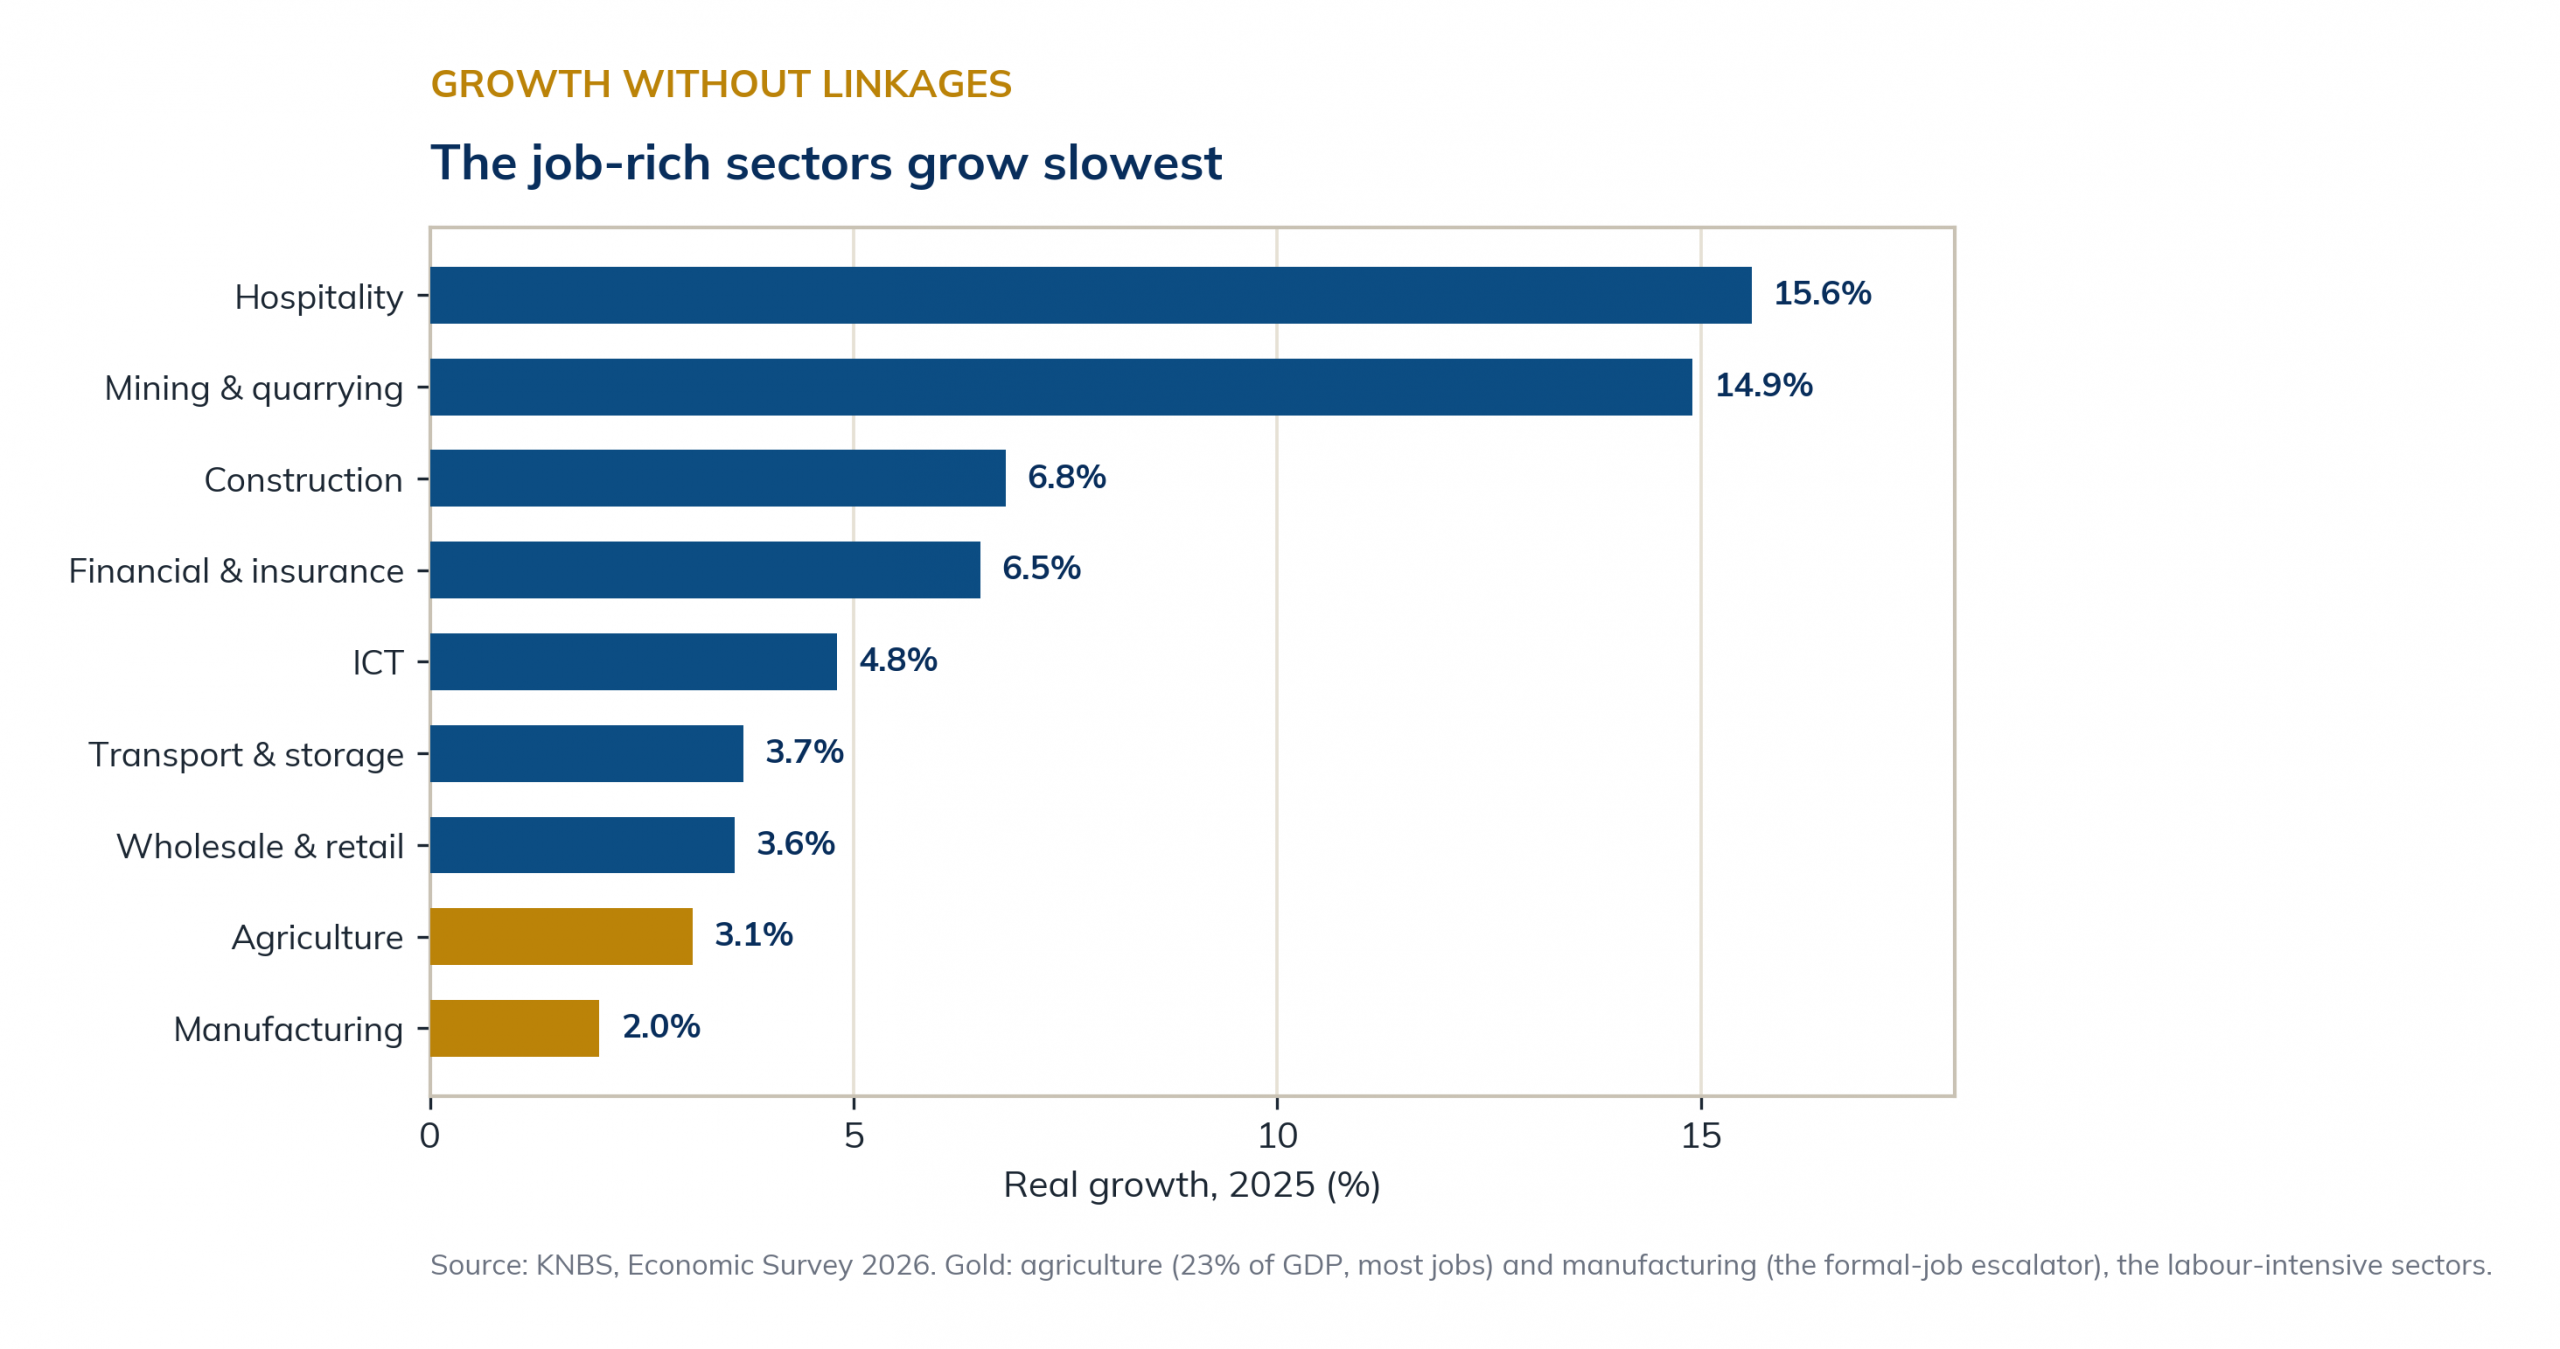
The composition of growth: the job-rich sectors grow slowest.

The composition of growth: the job-rich sectors grow slowest.

Here the two Kenyas come into full view. There is the Kenya of the data centre and the fintech founder, of regional headquarters and record capital, an African success the continent and the world have begun to notice. And there is the Kenya of the informal trader, the casual labourer and the jobless graduate. It is not only a divide of class but of geography, between a booming Nairobi and the arid counties of the north, between coast and highlands, a gap the devolution to 47 counties since 2010 was meant to close and has only begun to. In that other Kenya, 39.8 percent of people live below the poverty line. The inequality that matters here is less the national Gini, a moderate 38.5 by world standards and lower than it was twenty years ago, than its geography and its shape. Poverty runs from 16.5 percent in Nairobi to 82.7 percent in Turkana, a fivefold gap, and between those poles lies the whole country. The central highlands around Kiambu, Nyeri and Kirinyaga and the coastal hub of Mombasa all sit well below the national line; the western and Nyanza counties cluster near it; the Rift is uneven, Kericho jumping to 47.8 percent in a single year; and the arid north, Mandera, Samburu, Garissa, Tana River, Marsabit and Wajir, stands as a bloc above 64 percent.30 Underneath that map lies a second one, because poverty rates and population do not coincide. The largest numbers of poor Kenyans are spread across the populous counties: six of them, Nairobi, Kakamega, Bungoma, Nakuru, Kilifi and Turkana, hold about a quarter of all the poor between them, and rural Kenya carries 14.8 million of them against 5.4 million in the towns. The income that growth generates is concentrated too: the richest fifth of Kenyans take close to half of it, the poorest two-fifths about a seventh. Growth that pools in Nairobi and in the formal economy reaches that other Kenya, arid or rural, northern or simply crowded, only faintly; each point of national growth therefore buys less poverty reduction than the headline suggests, and the aggregate rises while the bottom waits. It is why years of respectable headline growth have coexisted with stubbornly high poverty. Consider the inflow that most flatters the macro picture: US$5.04 billion a year in remittances, the country’s largest single source of foreign exchange. That inflow is not idle money: it pays school fees and medical bills, which build human capital, and it seeds household savings and small-business capital, as the work on remittances and financial development finds. The weakness is one of intermediation: the money settles in consumption and housing rather than productive investment, and the instruments meant to convert it, the M-Akiba mobile bond, infrastructure and planned diaspora bonds, the Kenya Diaspora Investment Strategy 2025 to 2030, have so far underdelivered, M-Akiba in particular failing to draw subscribers. The binding constraint is the country’s financial structure, not the diaspora’s generosity.31 The question is whether the first Kenya pulls the second one up, or simply rises above it.
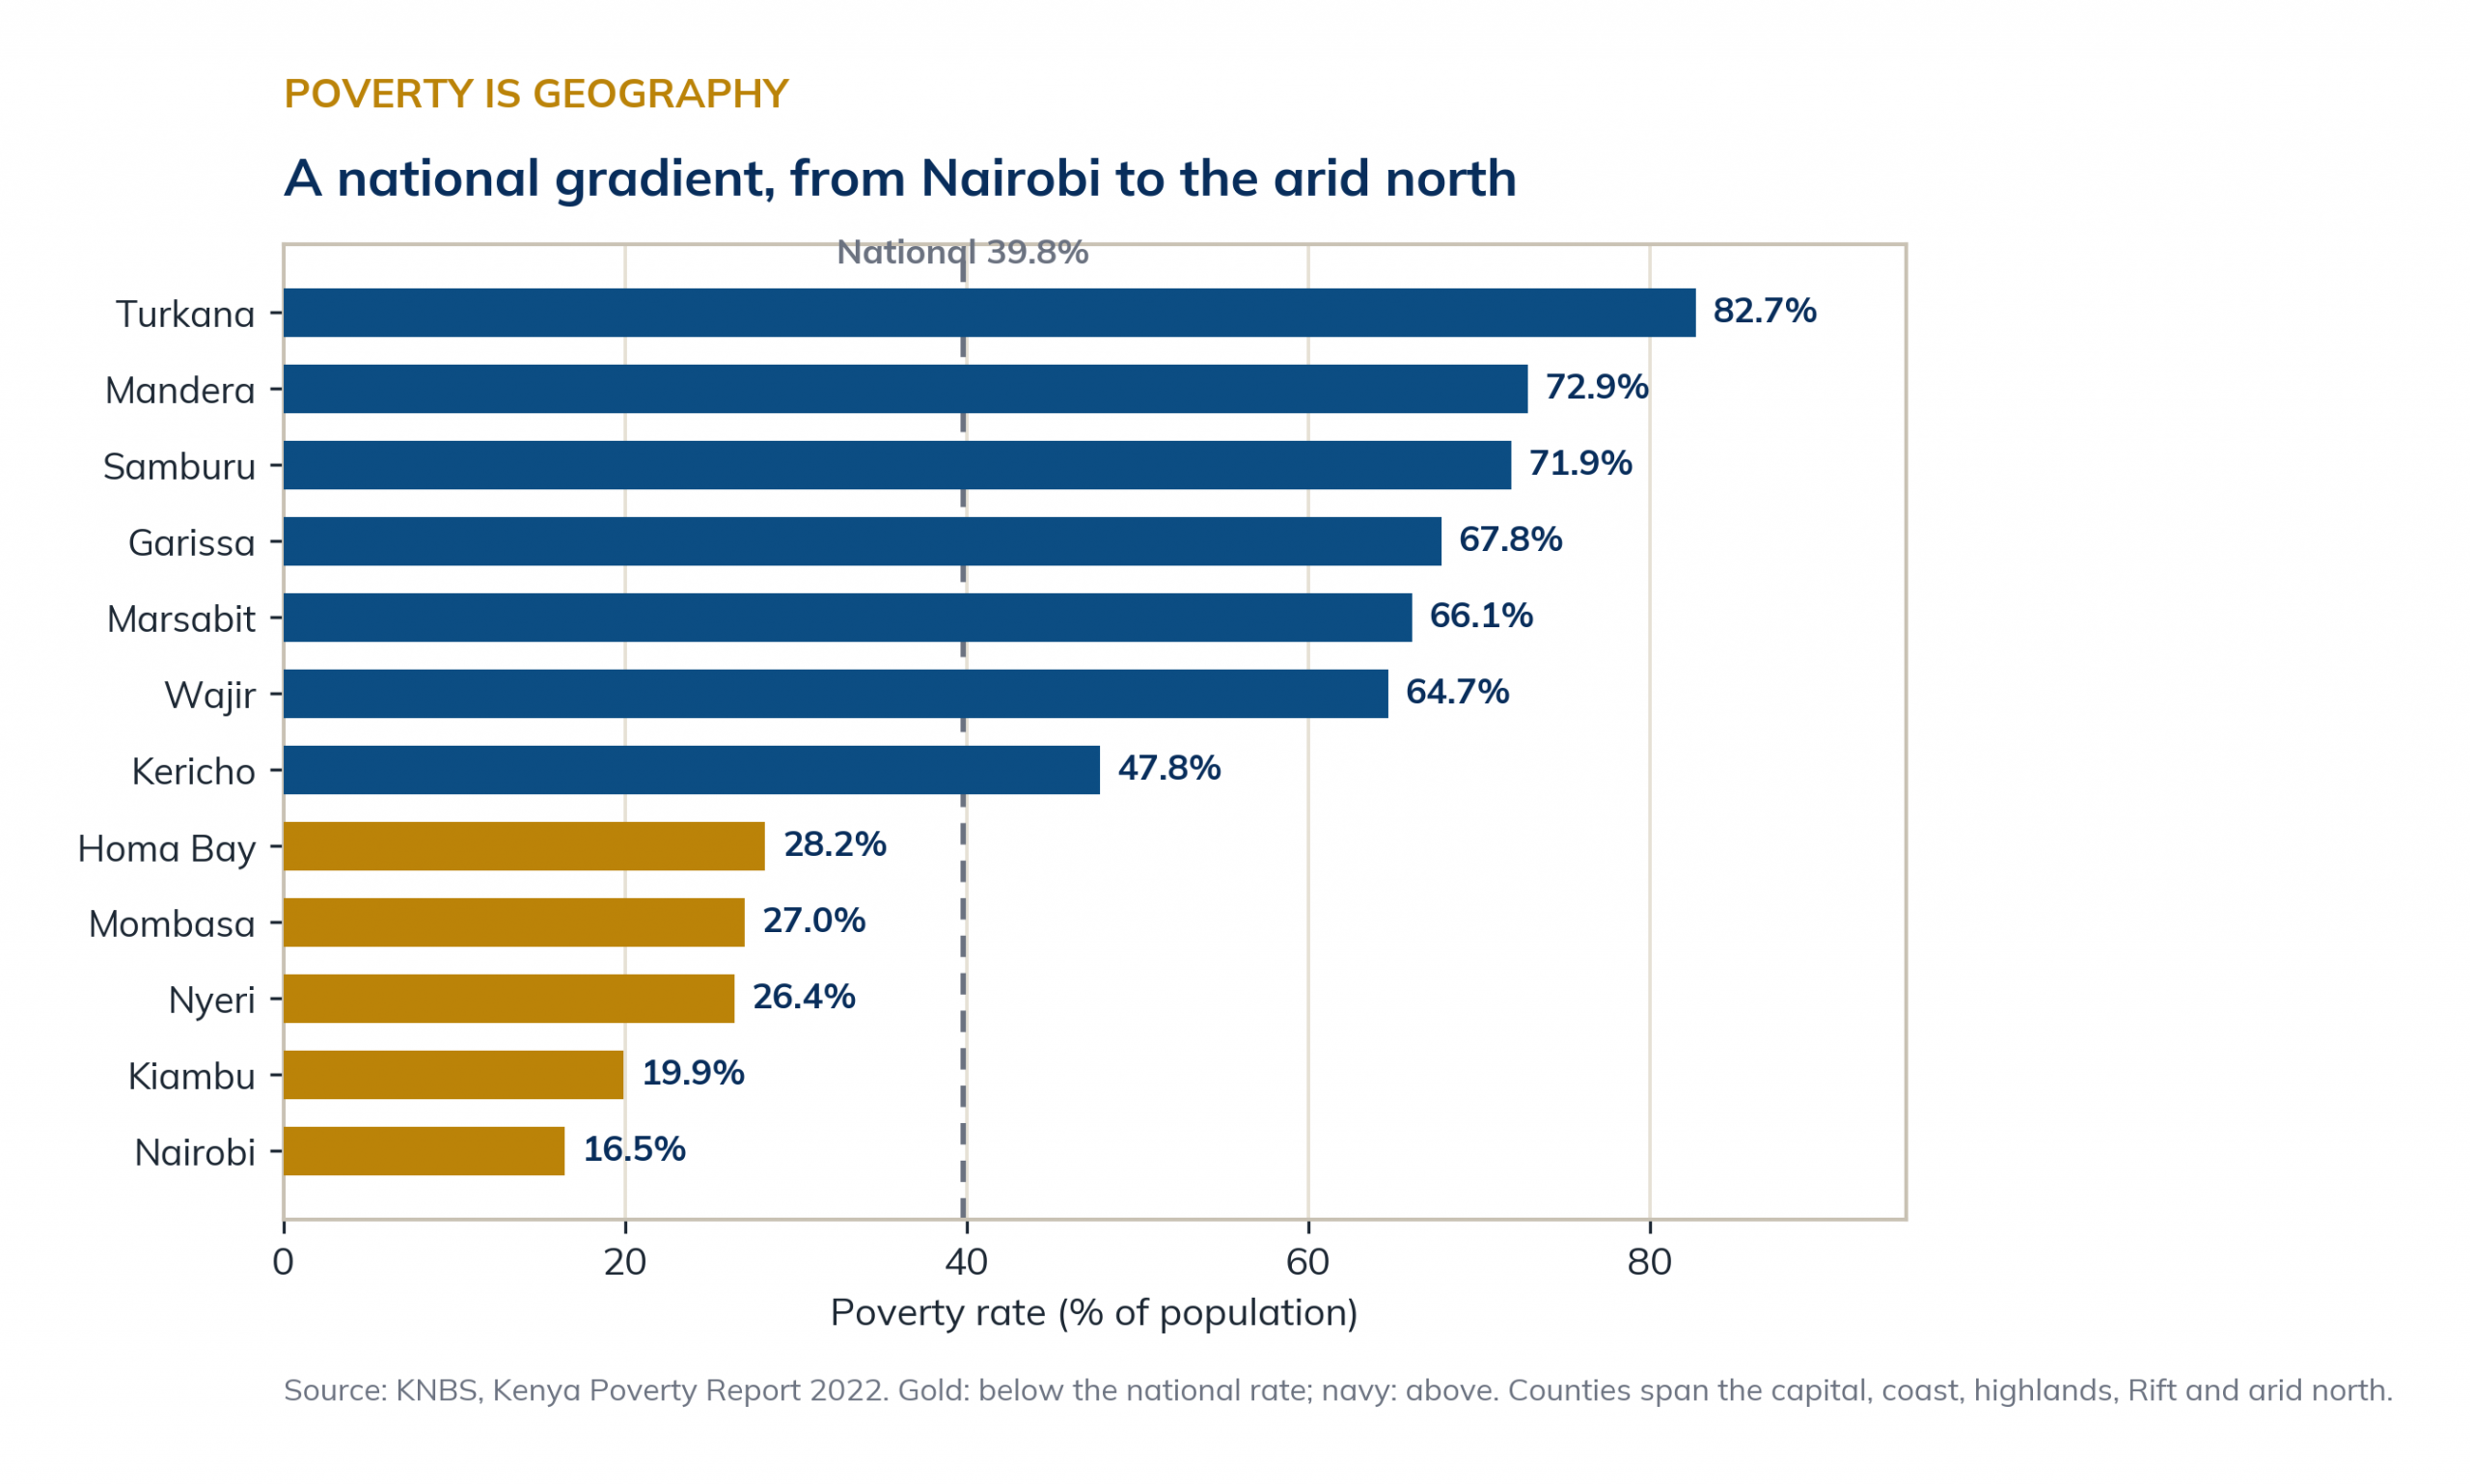
Poverty by county, 2022: Nairobi against the arid north.

Poverty by county, 2022: Nairobi against the arid north.

The sharpest version of this divide is not between Nairobi and the north at all. It is inside Nairobi. The county with the lowest poverty rate in the country is, by consumption, its most unequal: a Gini of 40.9 in 2021, the highest of any county and above the national figure.32 The reason is visible from any flight path into the city. Around 60 percent of Nairobi’s residents, on the order of two million people, live in informal settlements that cover roughly 5 percent of its land; Kibera, Mathare, Mukuru and Korogocho sit within walking distance of the glass towers and gated suburbs that define the city abroad.

The gradient runs across the city’s own map. Poverty falls to 7.3 percent in Makadara and 12.7 percent in Langata and climbs to 26.3 percent in Kibra, and even those constituency averages flatter the settlements they contain. Nor is the gap only money. Barely 22 percent of slum households have a piped-water connection, and most buy from vendors at prices higher than wealthier neighbourhoods pay; childhood immunisation runs at 58 percent in the informal settlements against 73 percent across the city. The Royal Nairobi Golf Course shares a fence with Kibera; the lawns of Karen and Muthaiga are a short drive from Mathare. The two Kenyas are not only a matter of the distance between the capital and Turkana. They live on the same street. It is no accident that the revolt of June 2024 was young and urban: the city that concentrates the country’s wealth concentrates, just as sharply, the gap between those who share in it and those who serve it.
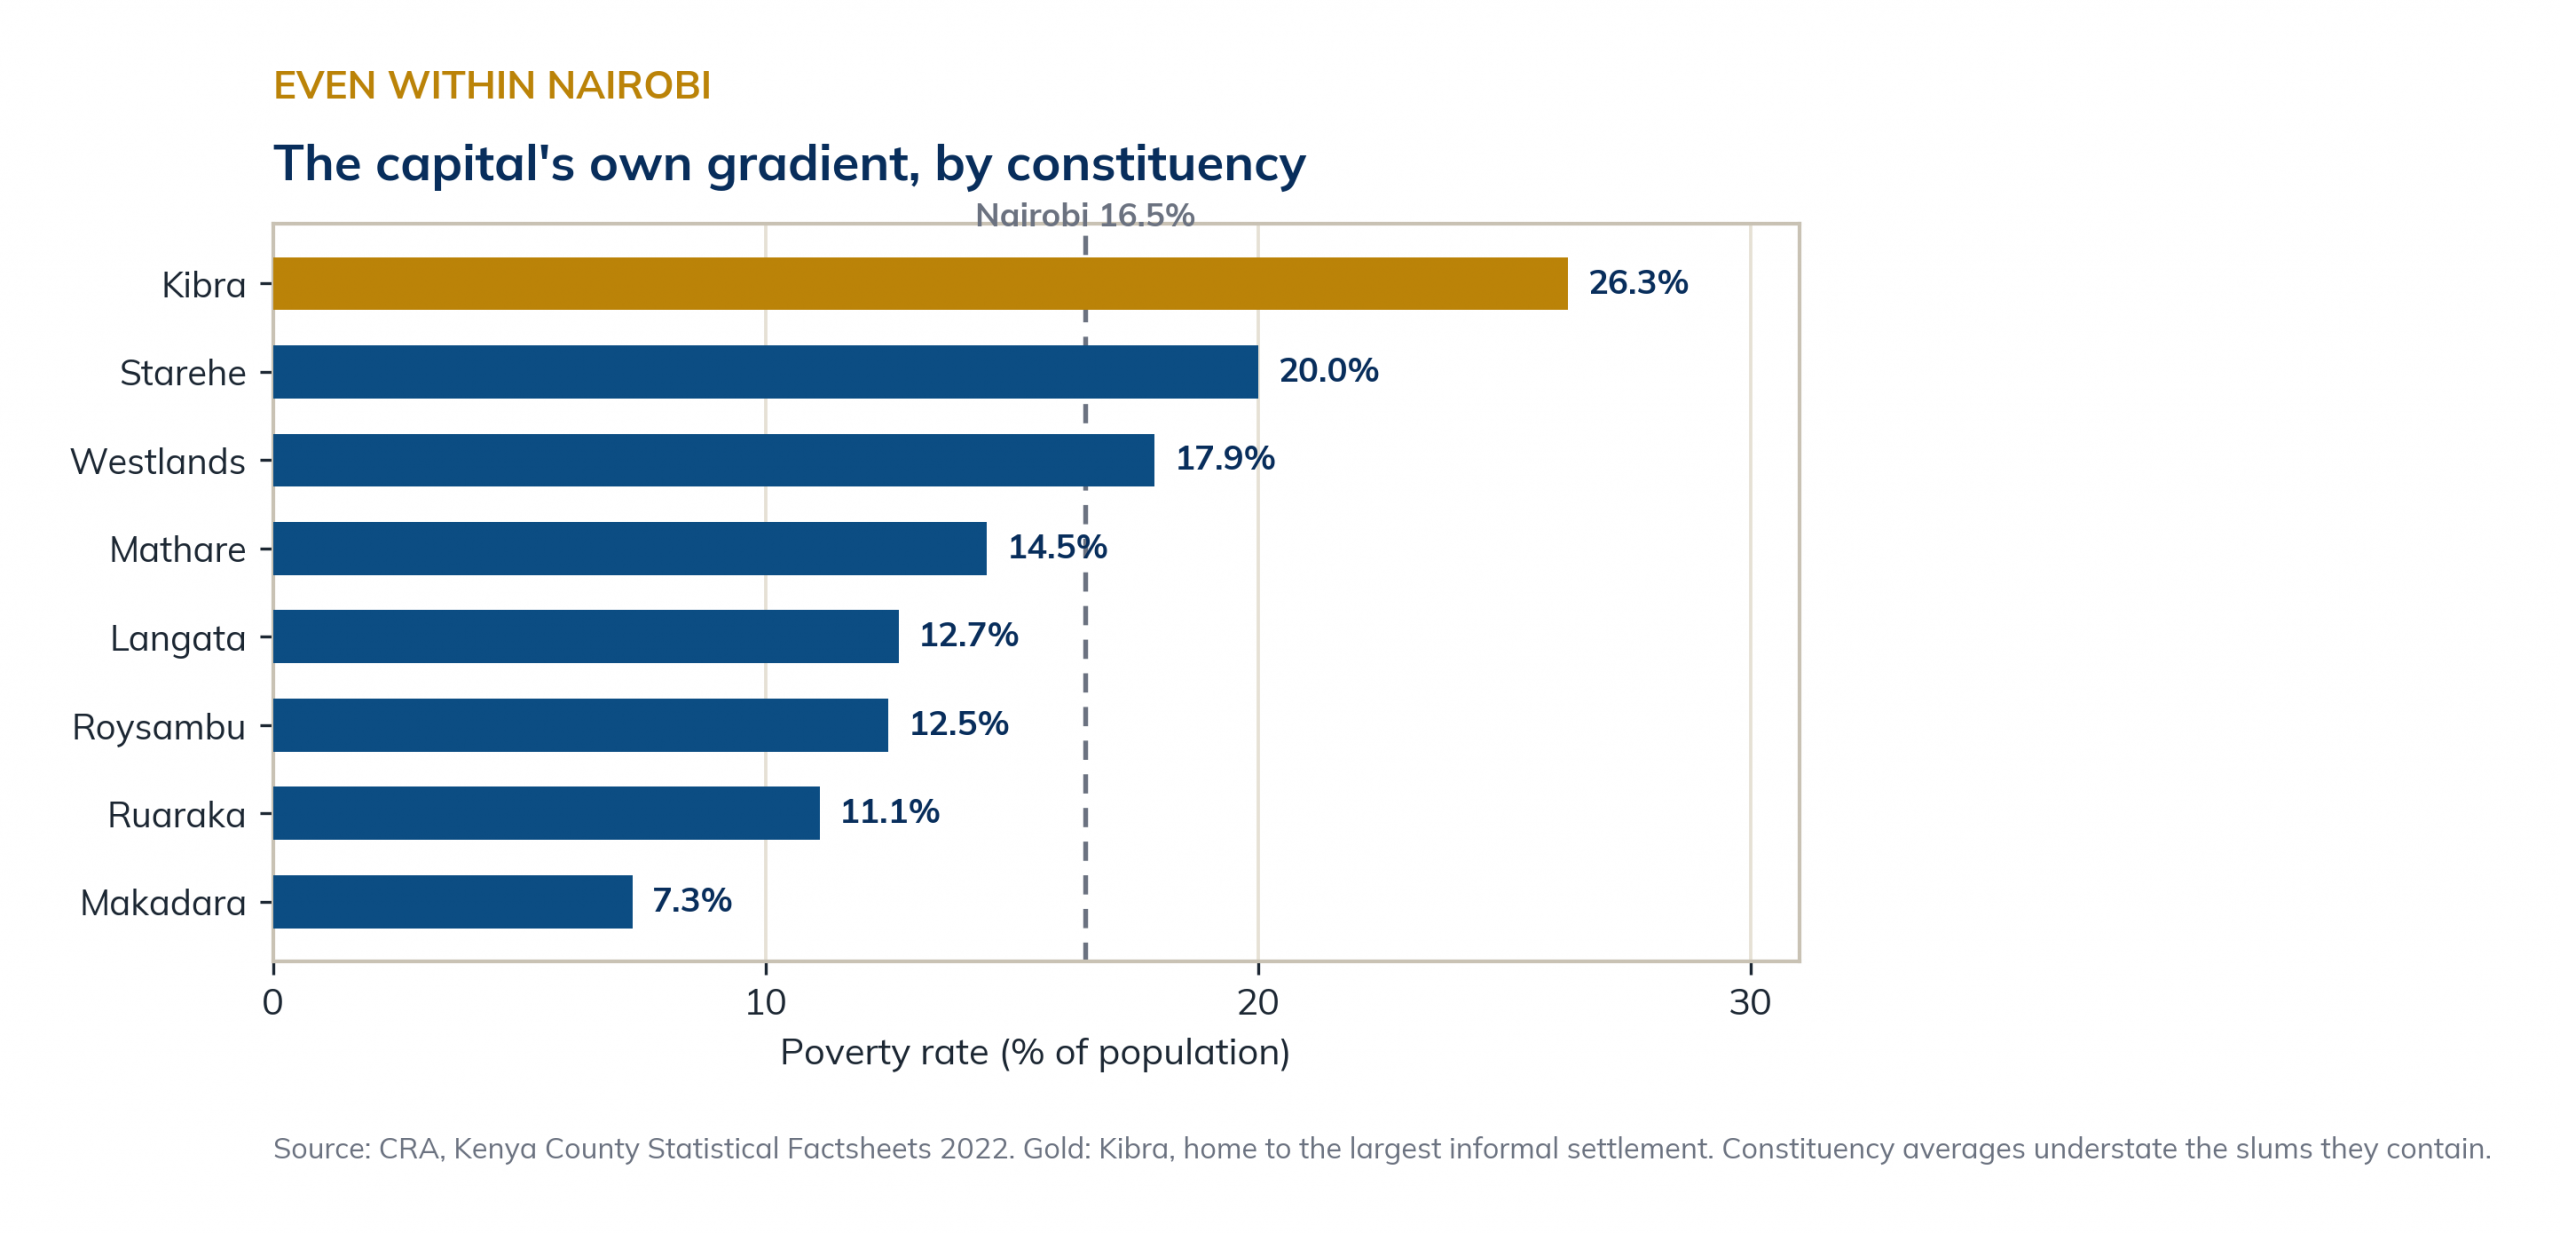
Within the capital: poverty by Nairobi constituency, 2022.

Within the capital: poverty by Nairobi constituency, 2022.

The summer the young refused to pay

In June 2024 that question stopped being abstract. When the government tried to close its budget gap with a finance bill stacked with new taxes, a leaderless generation organised on social media, took to the streets across the country and briefly stormed Parliament in Nairobi. Dozens were killed. The President withdrew the bill, and later let an IMF programme lapse.33 It was the most serious challenge to the state in a generation. Its grievances ran wider than tax, into corruption, police killings and the abductions that followed; but the economic core was unmistakable: a young, connected, taxpaying generation refusing to carry the cost of a model emerging without them. The episode carries a lesson no spreadsheet contains. Fiscal consolidation has a social limit, and a country whose public debt reached 67.8 percent of GDP by mid-2025, with the IMF projecting a climb toward 71.6 percent in 2026 and a high risk of distress, cannot simply tax its formal minority harder to escape the trap.34 Ordinary revenue is only about 14 percent of GDP, down from 18 percent a decade ago and far short of the 25 percent the East African Community treats as the mark, so a state this thin cannot both service its debt and build.35 The way out is not a heavier load on those already inside the net; it is to widen the net by formalising the economy, and to convert borrowing into the productive investment that pays for itself. That is an economic argument and, after June 2024, a political necessity.

What it would take for Kenya to grow differently

Four tools, one conclusion. Kenya’s growth is driven by piling on inputs rather than by rising productivity; it is capped by an investment rate that is too low; it creates jobs but overwhelmingly the wrong, informal kind; and it is shared through an unequal structure that dulls its effect on poverty. None of this denies the achievement, and the achievement is large. Kenya has the most diversified and most stable economy in its region, a payments revolution it gave the world, one of the cleanest power grids anywhere, a young population brimming with ambition, and a hard-won credibility its neighbours envy. This is not faint praise: it is precisely because Kenya is emerging for real that the shape of that emergence matters so much, for Kenyans and as a test the whole continent is watching.

Seen whole, these findings are not a list of complaints but a single system. Kenya grows by accumulation because it saves too little and taxes too thinly, and most of what it does raise is pre-empted by the service of its debt; it grows in the wrong sectors because the tradable, labour-intensive base that would lift both productivity and employment has thinned; and it grows in the wrong places because the gains pool in Nairobi and the formal economy. Each lock helps hold the others shut. Pull one alone and little moves; the levers have to turn together, which is the whole meaning of inclusive growth.

Table 3. The four gaps as one system: what keeps Kenya’s growth from reaching its people.

The gap What holds it shut What turning it would reach
Accumulation Savings near 13 percent and revenue near 14 percent of GDP, with debt service taking about 69 percent of revenue Investment capacity, mobilised at home through SACCOs, remittances and a wider tax base
Efficiency A capital-output ratio near 3.8, with capital aimed at non-tradables and consumption More growth from each shilling, if allocation shifts toward tradables
Composition Growth concentrated in low-linkage finance, ICT and mining, amid premature deindustrialisation Jobs and a higher poverty elasticity, through agro-industry and labour-intensive tradables
Geography Poverty of 16.5 percent in Nairobi against 82.7 percent in Turkana, and sharp divides inside Nairobi itself The arid, rural and informal Kenya, through devolution-targeted investment

Synthesis by the author. The fiscal lock, thin revenue and heavy debt service, runs across all four gaps.

Growing differently means four concrete things. Lift productivity, not just inputs, through skills, technology and the efficiency of firms. Raise the investment rate and aim it at tradable, productive capacity rather than consumption. Build the industrial base Kenya can actually compete on, agro-processing first and selective niches, the kind that turns informal workers into formal ones, rather than chase a mass-manufacturing model the world market no longer offers on the old terms. And pursue a pattern of growth whose gains actually reach the 4 in 10 still below the poverty line. That is not a call to grow faster. It is a call to grow better, and to grow together. Kenya has already won the contest of size, though that victory should be read with care: it holds at market exchange rates, while at purchasing-power parity Ethiopia, with more than twice the population, remains the larger economy. The harder contest is only beginning, and this first analysis has done no more than open it. Having grown this much, Kenya now faces the question its own streets put in June 2024: for whom does it grow next?

Table 4. Kenya and its East African neighbours, 2024-2025.

Indicator Kenya Tanzania Uganda Rwanda Ethiopia
GDP, US$ bn (2025) 136 87 64 15 109
Real growth 2024 4.7% 5.6% 6.1% 8.9% 8.1%
Real growth 2025 4.6% 6.0% 6.4% 7.5% 9.8%

GDP at current prices, IMF and Statista, 2025. Real GDP growth: KNBS, Economic Survey 2026 (Kenya), and African Development Bank, MEO 2026.

References

Adams and Page (2005). Do International Migration and Remittances Reduce Poverty in Developing Countries? World Development.

Amsden (1989). Asia’s Next Giant.

Datt and Ravallion (1992). Growth and Redistribution Components of Changes in Poverty Measures. Journal of Development Economics.

Easterly and Levine (2001). It’s Not Factor Accumulation. World Bank Economic Review.

Feenstra, Inklaar and Timmer (2015). Penn World Table.

Houngbonon and others (2013, 2014). Inclusive growth in Africa. L’Afrique des Idées; presented at UNU-WIDER (Helsinki, 2013) and the World Bank Annual Bank Conference on Africa (Paris, 2014).

Krugman (1994). The Myth of Asia’s Miracle. Foreign Affairs.

Loayza and Raddatz (2010). The Composition of Growth Matters for Poverty Alleviation. Journal of Development Economics.

McKinnon (1973). Money and Capital in Economic Development. Brookings Institution.

Rodrik (2016). Premature Deindustrialization. Journal of Economic Growth.

Shaw (1973). Financial Deepening in Economic Development. Oxford University Press.

Solow (1957). Technical Change and the Aggregate Production Function. Review of Economics and Statistics.

Studwell (2013). How Asia Works.

Young (1995). The Tyranny of Numbers. Quarterly Journal of Economics.

Notes

[1] Communications Authority of Kenya, Sector Statistics, June 2025; 76.7 million active SIM lines, penetration 146.3 percent.

[2] Communications Authority of Kenya and Central Bank of Kenya, 2025; 47.7 million active mobile-money accounts, M-Pesa 91 percent of the market.

[3] KNBS, Economic Survey 2026; informal work about 85 percent of total employment, 87.2 percent of jobs created in 2025.

[4] IMF and Statista, 2025; Kenya nominal GDP about US$136 bn (KES 17.58 trillion, KNBS) against Ethiopia about US$109 bn, whose dollar GDP fell after the July 2024 birr float (depreciation above 55 percent, World Bank).

[5] Launch Base Africa and industry trackers, 2024-2025; Kenya among the continent’s top destinations for startup capital, close to US$1 bn in 2025; rankings vary by tracker and year.

[6] EPRA, Energy and Petroleum Statistics, year to June 2025; renewables 80.2 percent of electricity, geothermal 39.5 percent.

[7] Central Bank of Kenya, 2025; diaspora remittances US$5.04 bn, up 1.9 percent, the single largest source of foreign exchange.

[8] KNBS 2019 census projections and World Bank; about 75 percent of Kenyans under 35, population about 56 million.

[9] African Development Bank, MEO 2026, and Table 4; among its major neighbours Kenya recorded the lowest 2025 growth.

[10] KNBS, Kenya Poverty Report 2022; poverty headcount 39.8 percent, Gini 38.5.

[11] Company announcements and press reports, 2024; Microsoft and G42 geothermal-powered data centre, the largest private digital investment in Kenya’s history.

[12] Kenya Flower Council and EU trade data; Kenya among the world’s leading cut-flower exporters.

[13] KNBS, Economic Survey 2026; real growth 5.7 percent (2023), 4.7 percent (2024), 4.6 percent (2025).

[14] African Development Bank, MEO 2026; East Africa growth 6.4 percent in 2025.

[15] KNBS and Central Bank of Kenya, 2025-2026; inflation averaged 3.8 percent in 2025, rising to 5.6 percent by April 2026; reserves US$13.24 bn, 5.6 months of import cover (June 2026).

[16] Growth accounting follows Solow (1957). On the residual, rather than accumulation, driving most cross-country income gaps, Easterly and Levine (2001); the accumulationist counterpoint, Young (1995) and Krugman (1994). Measured productivity is sensitive to capital-stock and depreciation assumptions (Feenstra, Inklaar and Timmer, 2015).

[17] Growth-accounting studies of Kenya (Solow and Cobb-Douglas framework), from the 1970s to recent work, with AfDB and KIPPRA productivity analyses; total factor productivity found weak, volatile and in several periods negative.

[18] World Bank, gross fixed capital formation (% of GDP); Kenya 17.7 percent in 2024; high-growth comparators shown at their take-off decades.

[19] World Bank, gross domestic savings about 13 percent of GDP (2024); SASRA, SACCO Supervision Report 2024, regulated SACCO assets KES 1.076 trillion, 7.39 million members.

[20] On savings mobilisation through financial repression and directed credit in the East Asian model, McKinnon (1973) and Shaw (1973); Amsden (1989); Studwell (2013).

[21] National Treasury and Controller of Budget, FY2024/25; debt service about 69 percent of ordinary revenue (KES 1.72 trillion) against the IMF threshold of 30 percent; interest payments up from 18 to 25 percent of public spending in four years.

[22] KNBS, Economic Survey 2026; 822,100 jobs created in 2025, 716,800 informal (87.2 percent), wage employment 15.3 percent of 21.6 million, real-wage index 85.84 (2009=100).

[23] KNBS, Economic Survey 2026, and Kenya VNR 2024; manufacturing 7.1 percent of GDP in 2025, down from 11.5 percent in 2009, growth of 2 percent, against the Vision 2030 target of 15 percent.

[24] Kenya Association of Manufacturers, Exports Competitiveness Study, 2025, estimating about KES 684 billion in untapped export potential and flagging Mombasa-corridor logistics and energy costs; on premature deindustrialisation as a global-trade phenomenon, Rodrik (2016).

[25] Apparel exports to the United States rose from about US$55 million in 2001 to US$603 million in 2022, roughly two-thirds of Kenya’s US exports, under AGOA, which lapsed in 2025 (US International Trade Commission; KNBS). Tea and cut-flower standing: International Trade Centre and Kenya Flower Council.

[26] Decomposition following Datt and Ravallion (1992). The Gini fell from 46.5 (2005) to 38.5 (2022): World Bank Poverty and Inequality Platform and KNBS.

[27] KNBS, Economic Survey 2026: 2025 real growth, financial and insurance 6.5 percent and information and communication 4.8 percent, against agriculture 3.1 percent and manufacturing 2.0 percent; manufacturing 7.1 percent of GDP in 2025, down from 11.5 percent in 2009.

[28] On the composition of growth and poverty, Loayza and Raddatz (2010).

[29] L’Afrique des Idées study on inclusive growth in Africa, Houngbonon and others (2013, 2014).

[30] KNBS, Kenya Poverty Report 2022: poverty 16.5 percent in Nairobi, 19.9 percent in Kiambu, 27.0 percent in Mombasa, 28.2 percent in Homa Bay, 47.8 percent in Kericho, up to 82.7 percent in Turkana; six populous counties (Nairobi, Kakamega, Bungoma, Nakuru, Kilifi, Turkana) hold about a quarter of all poor Kenyans; rural poor 14.8 million against 5.4 million urban. Income shares, World Bank Poverty and Inequality Platform: top quintile about 48 percent, bottom 40 percent about 14 percent.

[31] On remittances and poverty, Adams and Page (2005); on the Kenyan link between remittances and financial development, a 2019 study in Financial Innovation. M-Akiba, the first mobile-phone bond, drew low subscription; the Kenya Diaspora Investment Strategy 2025-2030 shifts the aim from remittances to investment.

[32] Nairobi consumption Gini 40.9, the highest of any county (KNBS, KCHS 2021), above the national 38.5; UN-Habitat and KENSUP, about 60 percent of Nairobi residents in informal settlements on roughly 5 percent of the land, 22 percent of slum households with a piped-water connection; Amnesty International 2019, about 2 million residents in informal settlements; constituency poverty, CRA Kenya County Statistical Factsheets 2022 (Makadara 7.3, Langata 12.7, Kibra 26.3); immunisation 58 against 73 percent, Nairobi Cross-Sectional Slum Survey 2012, APHRC.

[33] Press reports, June 2024; withdrawal of the Finance Bill after nationwide protests, and the subsequent lapse of the IMF programme.

[34] National Treasury, Annual Public Debt Report 2024/25; public debt 67.8 percent of GDP at end-June 2025; IMF April 2026 REO projects 71.6 percent in 2026; high risk of distress.

[35] National Treasury, Medium Term Revenue Strategy: ordinary revenue fell from 18.1 percent of GDP (FY2013/14) to 14.1 percent (FY2022/23); the East African Community target is 25 percent, sought by 2030.

Africa’s mobile money revolution has outgrown its rules

The growth of mobile money in sub-Saharan Africa over the past decade has been extraordinary, both in scale and in its effects on welfare. According to the World Bank’s Global Findex 2025, 58% of adults in the region now hold a financial account, up from 34% in 2014, with mobile money accounting for the bulk of that expansion. The GSMA’s 2026 industry report records 2.3 billion mobile money accounts worldwide, with Africa concentrating roughly two-thirds of global transaction volumes (approximately $1.4 trillion in 2025 alone). These are not marginal figures. They represent a fundamental shift in the way financial services reach populations that the traditional banking sector has largely failed to serve. The impact of this shift on poverty and resilience is supported by rigorous empirical evidence. Suri and Jack (2016), in a widely cited study published in Science, showed that access to M-Pesa in Kenya lifted 194 000 households out of extreme poverty, with particularly strong effects for female-headed households. Earlier, Jack and Suri (2014) had established in the American Economic Review that non-users of M-Pesa experienced a 7% decline in consumption following negative income shocks, whereas users were largely unaffected, the mobile wallet functioning, in effect, as a mechanism for risk-sharing within family networks.

Mobile money has clearly delivered genuine gains in financial inclusion. The question this article seeks to address is different: whether the regulatory frameworks governing mobile money operators across Africa are adequate for the risks these operators now carry. The answer, upon close examination, is that while meaningful regulation exists (more than is generally appreciated), several critical gaps remain. These gaps are not negligible, and they matter for the stability of the financial system, for the real economy, and for the operators themselves.

A look back at history. It started in Kenya, when Safaricom launched M-Pesa in 2007. Few predicted it would become the most studied financial innovation in the developing world. But the evidence is now overwhelming. The mechanism is elegant: mobile money makes transfers within family networks faster and cheaper, turning the handset into an informal insurance system. The innovation then spread westward. In Senegal, the arrival of Wave in 2018 sent shockwaves through the market. Transfers at 1%, deposits and withdrawals free of charge: within a few years, the fintech had amassed 21 million monthly active users and deployed 150000 agents across eight countries. Orange and MTN, caught off guard, were forced to match. In Côte d’Ivoire, they ended up scrapping withdrawal fees altogether. In October 2025, Wave crossed a symbolic threshold: it created Wave Bank Africa S.A., a fully licensed commercial bank headquartered in Abidjan with CFA 20 billion in capital. From mobile wallet to banking licence, a trajectory worth watching closely. In Rwanda, the interoperability platform ekash helped push financial inclusion from 21% to 90%, one of the most dramatic leaps on the continent. In Togo, rated “very high” on the GSMA’s Mobile Money Prevalence Index, Gozem Money launched in 2025 and Mixx Togo inaugurated instant payments via the BCEAO’s regional PI-SPI platform. In the DRC, financial inclusion stands at 58%, but actual bank penetration barely reaches 25%: the gap is filled entirely by mobile money. In Burkina Faso, Ky, Rugemintwari and Sauviat (2018) found that mobile money increases the propensity to save, though, as we shall see, the channel through which savings flow matters considerably. In Togo specifically, Meli, Kamga and Meli (2024), confirmed the spread of mobile money adoption while noting that income, education and gender remain powerful determinants of who gets in, and who does not. The progress is real. The question is not whether mobile money works. It does. The question is whether the regulatory architecture behind it remain relevant to preserve financial stability.

Rules exist and play a critical role in mobile money development. Evans and Pirchio (2015), studying 22 countries, showed that regulation is often the decisive factor in whether mobile money takes off or stalls. The IMF’s 2025 departmental paper on digital payment innovations in sub-Saharan Africa confirms the point: differences in regulatory approach, whether a country protects incumbents or enables new entrants, explain much of the divergence in adoption trajectories across the continent (Ricci et al., 2025). In the WAEMU zone, for example, the BCEAO built a structured framework around Instruction No. 008-05-2015. Only licensed Electronic Money Issuers (EMIs), banks and authorised microfinance institutions may issue e-money. The minimum capital requirement is CFA 300 million (roughly 440 KEUR). Client funds must be ring-fenced: at least 75% held in demand deposits at commercial banks, the remainder in term deposits or treasury bills. The EMI may not lend, may not pay interest on balances, and may not use client funds for its own purposes. The WAEMU Banking Commission monitors two key ratios: a coverage ratio (equity must be at least 3% of outstanding e-money) and an equivalence ratio (ring-fenced funds must cover 100% of outstanding e-money). A 2024 update, Instruction No. 001-01-2024, tightened anti-money laundering obligations and created a new payment institution licence. Elsewhere, approaches differ. In Kenya, the Central Bank of Kenya supervises M-Pesa under the National Payment System Act of 2011. Client funds are deposited in trust accounts at commercial banks, a model unique on the continent. Interest generated on those funds flows to a charitable foundation rather than to Safaricom’s bottom line. It is worth emphasising that the welfare gains documented by Suri and Jack were observed within this supervised environment, not in the absence of regulation. Ghana ranks first in Africa on the GSMA’s 2024 Mobile Money Regulatory Index. Nigeria, long wedded to a bank-led model, opened the door to telecom operators in 2021; in January 2026, the neobank Kuda secured a full national banking licence from the CBN, following the same trajectory as Wave in Côte d’Ivoire.

All of this is serious. But look closer. In May 2023, the WAEMU Banking Commission held its first-ever meeting with the chief executives of the region’s EMIs, eight years after the founding Instruction. One number from that meeting should have attracted more attention than it did. The equivalence ratio, the metric that measures whether outstanding e-money is fully backed by deposited funds, stood at 82.5%, against a regulatory target of 100%. Four out of ten EMIs were non-compliant. In plain terms: across a zone spanning eight countries from Senegal to Togo, nearly a fifth of circulating electronic money was not fully backed. For a system whose fundamental promise is instant convertibility into cash, this is a warning signal. Banks, one might object, also run liquidity mismatches, and that is, after all, the essence of banking, which transforms short-term deposits into long-term loans. True. But banks have safety nets to manage that risk: calibrated liquidity ratios (the LCR and NSFR under Basel standards), access to central bank refinancing as a lender of last resort, and deposit insurance schemes. My own research on liquidity regulation in European banking (Ananou et al., 2021, 2023) has shown that the introduction of liquidity requirements, leads to measurable reductions in bank default risk, primarily through improved capitalisation and funding structure. EMIs, by contrast, operate without any of these backstops. When the float is not fully covered, there is no safety net.

The problem deepens when you examine deposit protection. In the WAEMU zone, the FGD-UMOA covers deposits held at banks. But what happens if an EMI fails? Ring-fenced funds are held in accounts in the EMI’s name, not in the name of individual customers. Legally, the customer of Orange Money or Wave is not a depositor in the prudential sense: they are a creditor of the issuer, holding a promise of repayment. In insolvency, they would rank as general creditors, not as guaranteed depositors.[1] The CGAP, in its reference study on client fund protection, puts it plainly: the treatment of e-money float by deposit guarantee schemes is not entirely clear. A necessary caveat: deposit insurance in Africa is itself a young mechanism. The WAEMU scheme has never been tested by a major bank failure. Kenya’s deposit insurance corporation has limited resources. The point is not that banks are perfectly protected and EMIs are not. The point is that for EMIs, the legal question has not even been settled.

More troubling still is the absence of resolution frameworks. In the WAEMU zone, banks have had a crisis resolution mechanism since 2015. In Kenya, the CBK has comparable tools. But across the continent, no regulator has created a resolution framework specific to mobile money operators. No preventive recovery plans. No mechanism to transfer customer accounts to another provider if an operator fails. If Wave, with its 21 million users, or MTN MoMo, with its daily volumes, were to face distress, supervisory authorities would have no legal instrument to organise an orderly transition. The only tool available is licence revocation, which is a punishment, not a crisis management device.

The question of systemic risk compounds these concerns.[2] The flows between banks and mobile money operators have reached proportions that make the exclusion of EMIs from macro-prudential surveillance increasingly difficult to justify. Global transfers between bank accounts and mobile wallets exceeded $160 billion in each direction in 2025. Ky, Rugemintwari and Sauviat (2025), studying 141 banks across the East African Community, found that bank performance is positively correlated with involvement in mobile money, but that this association operates through bank-operator partnerships, implying growing mutual dependence. Kulu et al. (2022) confirmed this interdependence in Ghana as well.

Finally, there is the question of fraud and algorithmic lending. In August 2025, a viral campaign (#StopAirtelThefty) erupted in Uganda after cases emerged of stolen phones being used to drain Airtel Money accounts and fraudulently subscribe to loans, without enhanced identity verification. The GSMA acknowledges that 19% of mobile phone owners in low- and middle-income countries report receiving scam or extortion messages. In sub-Saharan Africa, roughly half of mobile money account holders do not protect their phone with a password. Meanwhile, 44% of mobile money providers now offer credit, often using machine-learning models that score customers based on transaction histories. No central bank on the continent has published guidance on the use of artificial intelligence in mobile lending. The technology is moving. Regulation has not caught up yet.

And then there is the tax question. In September 2025, Senegal’s National Assembly adopted a fiscal reform that increased taxation on mobile money transactions. Wave disclosed it had paid over CFA 30 billion in taxes in Senegal in 2024 alone. The tension is real and plays out across the continent: Uganda, Cameroon, Côte d’Ivoire and Tanzania have all experimented with mobile transaction levies, with documented effects on transaction volumes and a documented push back towards cash. The structural dilemma is clear: mobile money creates a visible tax base, but taxing it too aggressively risks undermining the very inclusion it has enabled. We a piece on that worth reading.

One might be tempted to dismiss these gaps as technical, even theoretical. They are not. Merchant payments via mobile money reached $155 billion in 2025. Bulk disbursements (salaries, subsidies, social transfers) exceeded $139 billion. International remittances through mobile channels totalled $45 billion. These are no longer person-to-person transfers: they are the rails on which entire economies run. Mobile money is not a complement to the financial system. It is the financial system for millions of people. A prolonged outage or operator failure would have immediate macroeconomic consequences: blocked salary payments, disrupted supply chains, interrupted social transfers.

Financial stability is also at stake. If an EMI were to withdraw its ring-fenced deposits from a bank (say, by switching partners), it would create a liquidity shock. If a bank holding ring-fenced funds were to fail, it would be mobile money customers’ funds that are exposed. The channel is bidirectional. It is supervised by no dedicated instrument. Importantly, Ky, Rugemintwari and Sauviat (2021), using individual-level survey data from Burkina Faso, found that mobile money users are not more likely to make deposits in formal financial instruments. The mobile money system and the formal banking system coexist as parallel rails rather than as a pipeline from informal to formal finance. This finding challenges the widely held assumption that mobile money serves as a “stepping stone” toward banking. It also has a regulatory implication: if mobile money creates a durable parallel financial circuit rather than feeding into the supervised banking system, then that circuit itself requires appropriate prudential safeguards.

The operators themselves appear to recognise this. Wave’s creation of a bank in Côte d’Ivoire and Kuda’s acquisition of a banking licence in Nigeria are not incidental decisions. These players are actively seeking entry into the regulated banking perimeter, because they understand that the ability to lend, collect deposits, and diversify revenue requires the institutional credibility that a banking licence confers. However, the majority of mobile money operators will not become banks. They will remain EMIs, and it is the EMI framework that needs strengthening.

Mobile money is one of the most important financial innovations Africa has known. From Kenya to Senegal, from Rwanda to the DRC, its impact on inclusion is established by research and visible to the naked eye. African regulatory frameworks are more structured than commonly assumed. But they were designed for a nascent ecosystem, and that ecosystem has outgrown its rules.

Three priorities stand out. First, clarify the legal status of customer funds: are mobile money users depositors or creditors? The answer to that question conditions everything else. Second, create resolution mechanisms specific to mobile money operators, including preventive recovery plans and account portability devices, because licence revocation is not crisis management. Third, bring the largest operators into the macro-prudential surveillance perimeter when their transaction volumes make them systemically important in practice. The goal is not to slow inclusion. It is to make it durable.

References

Ananou, F., Chronopoulos, D., Tarazi, A., Wilson, J.O.S. (2021). Liquidity regulation and bank lending. Journal of Corporate Finance, 69(1), 101997.

Ananou, F., Chronopoulos, D., Tarazi, A., Wilson, J.O.S. (2023). Liquidity regulation and bank risk. Working paper, LAPE/University of St Andrews.

Evans, D.S. & Pirchio, A. (2015). An Empirical Examination of Why Mobile Money Schemes Ignite in Some Developing Countries but Flounder in Most. Review of Network Economics, 13(4).

Jack, W. & Suri, T. (2014). Risk Sharing and Transactions Costs: Evidence from Kenya’s Mobile Money Revolution. American Economic Review, 104(1).

Kulu, E. et al. (2022). Mobile money transactions and banking sector performance in Ghana. Heliyon, 8(10).

Ky, S.S., Rugemintwari, C. & Sauviat, A. (2018). Does mobile money affect saving behaviour? Evidence from a developing country. Journal of African Economies, 27(3).

Ky, S.S., Rugemintwari, C. & Sauviat, A. (2021). Friends or Foes? Mobile money interaction with formal and informal finance. Telecommunications Policy, 45(1).

Ky, S.S., Rugemintwari, C. & Sauviat, A. (2025). Is Fintech Good for Bank Performance? The Case of Mobile Money in the East African Community. IJFE, 30(4).

Meli, S.D., Kamga, B.F. & Meli, C.N. (2024). Determinants of Mobile Money Adoption and Use: Evidence from Togo. Journal of the Knowledge Economy.

Suri, T. & Jack, W. (2016). The long-run poverty and gender impacts of mobile money. Science, 354(6317).

World Bank (2025). Global Findex Database 2025.

IMF (2025). Digital Payment Innovations in Sub-Saharan Africa. Departmental Paper 2025/004.

GSMA (2024). Mobile Money Regulatory Index 2024.

GSMA (2026). State of the Industry Report on Mobile Money 2026.


[1] When a customer deposits money at a bank in Abidjan, Nairobi or Accra, that deposit is explicitly covered by a guarantee scheme up to a defined ceiling. When the same customer loads a mobile wallet (Wave, M-Pesa, Orange Money), they hold a claim on the issuer: a contractual promise of repayment. Ring-fencing protects against misappropriation of funds. It does not protect against insolvency. The distinction is not academic; it determines whether customers recover their money when an operator fails.

[2] Systemic risk refers to the possibility that the failure of a single institution could, through contagion effects, destabilise the broader financial system. Following the 2008 global financial crisis, regulators worldwide developed frameworks to identify systemically important institutions, i.e. those whose failure could propagate losses across the system. In Africa, this designation applies exclusively to banks. Mobile money operators are not subject to it, even when the volumes they process are comparable to those of mid-sized banks.

Entretien avec Lionel Yao, fondateur de S-Cash Payment

L’Afrique des Idées a rencontré S-Cash Payment, une solution bancaire, totalement digitale. Son fondateur Lionel Yao, revient dans cet entretien sur le rationnel derrière la mise en place de cette plateforme.

ADI : En quoi consiste votre initiative, pourriez-vous nous donner un aperçu général de vos activités ?

Nous avons développé le premier compte sans banque 100% mobile pour les personnes exclues des systèmes financiers classiques, afin de leur permettre de bénéficier de solutions d’épargne, de crédits et d’un porte-monnaie électronique permettant d’acheter 24h sur 24 sans prendre le risque de transporter de la liquidité sur soi. Ce projet nous a couté plus de 25 millions Franc CFA jusqu’à présent. 

D’où vous est venue l’idée de fonder S-Cash Payment ? 

En 2015 lors d’un voyage au Nigeria en bus, j’ai été frustré et peiné parce que je ne disposais pas de compte bancaire, ni de produit bancaire comme les cartes de crédit pour effectuer mes transactions en naira. Ce constat m’a amené à chercher une solution dématérialisée  qui pourrait répondre aux problèmes de tous ceux qui étaient ou se retrouveraient dans ma situation. En faisant les recherches, je me rendu compte qu’en Afrique, on dénombre 925 millions de personnes non bancarisées en Afrique dont 420 millions en Afrique subsaharienne alors que 277 millions possèdent des smartphones et un compte mobile Money. Dès lors la solution que nous voulions proposer était possible et se justifiait. C’est dans cette optique que mon équipe (2 financiers et 3 codeurs) et moi, avions décidé de nous investir totalement pour créer S-Cash.

L’administration vous a-t-elle aidé dans vos démarches ?

Nous avons obtenu un fonds d’amorçage auprès de la fondation jeunesse numérique (www.fjn.ci), on espère plus dans le future. Au delà, d’un intérêt réel pour notre projet, nous n’avons pas reçu pour l’heure d’autres concours de l’Etat. Il n’y a pas de dispositifs d’appui concrets à des initiatives comme la nôtre malheureusement ; cela aurait été le bienvenu.

Quels sont les retours que vous avez eu sur votre projet ?

Nous avons seulement lancé pour le moment la version test (MVP) pour acquisition client. En termes de commercialisation véritable cela se fera dans les mois à venir. Nous recevons chaque jours de nos leads des messages nous demandant l’horizon de commercialisation de S-Cash car impatient d’utiliser la solution. Seules les banques demeurent réticentes à l’ouverture de leur système par peur des cybers attaques.

Comment voyez-vous l’avenir de S-Cash Payment ?

Je vois S-Cash comme une entreprise leader et experte dans la fourniture de solutions de finances digitales pour promouvoir l’inclusion financière en Afrique. Après la conquête du marché national, nous avons pour but de nous étendre sur toute l’Afrique subsaharienne !

Une dernière chose que vous souhaitez ajouter ?

La solution S-Cash est toujours en phase test et ne sera commercialisée que cette année. Mais nous avons déjà récolté un investissement de plus de 35 millions Franc CFA. Et nous restons ouverts à tout investisseur qui souhaiterait appuyer notre initiative pour contribuer à renforcer l’inclusion financière en Afrique.

Pour suivre le développement de S-Cash Payment, suivre leur page sur Facebook : @scash4you, Twitter: @scashpayment ou Instagram: @scash_payment

Potential, policies, financing and de-risking in Renewable Energy sector in Africa

600 million Africans have no access to electricity while the energy sources, especially renewable energies (RE) abound on the continent. Its key features: environment friendly, availability and its recent cost competitiveness gains over fossil energy; make renewable energy an excellent avenue to start an energy revolution in African. However, having affordable, sustainable and smooth access to energy has a cost. Public policy in investments promotion and risk mitigation in the RE sector are among other issues on which African Government should work on.
nThis study evaluates the potential of the continent in terms of renewable energy source, assesses the investment needs in light of the renewable energy targets of African countries and presents a set of recommandations to ensure these could be reached. Read the full note.
n

South Sudan’s existential fiscal crisis and possible remedies

This brief discusses key fiscal practices which should be addressed urgently to save South Sudan from chronic economic disasters. After many years of war with successive repressive regimes in Khartoum, South Sudan attained independence in 2011. The young nation immediately faced challenges in creating institutions and operating them in an environment of weak enforcement and compliance.

Lack of robust coordination among key institutions of economic governance, weak oversight institutions encourage mismanagement of resources with impunity which partly accounted for the onset of the 2013 conflict. To provide steady resource needed for reconstruction and sustainable development investment and mitigate fiscal crises, the government of South Sudan needs to implement strategies conducive of healthier public finances, including expenditure control to avoid overspending, pruning agency-shopping and improving tax collections through administrative reforms. Building institutions is not a spontaneous act but rather a contextual endeavour, which exacts both time and resources. Read the full Policy Brief.

The State Of Democracy in Africa: half in Earnest, half in Jest

n In 2017, what can be said about the democratic situation in African States? Whereas some countries are strengthened year after year, the democratic benefits often obtained come with difficulty and lots of sacrifices. Others don’t succeed in breaking free from the long-lasting and important lingering odour of authoritarianism. Whereas we witness pacific transfers of power and democratic alternations in some countries, we still deal with political leaders who use clever processes to unduly prolong their position as heads of the state. This is the demonstration that the obsession of power remains a perennial issue in the head of lots of political authorities in Africa. It shall be first specified that the democratic health condition of African countries cannot be determined only with regard to free and transparent elections in those countries. This would be  a really minimalist and subjective conception of democracy.

n

n The Good Performers of Democracy in Africa

n

n Ghana and Benin experienced last year, pacific elections and a democratic alternation at the head of the state. In these two countries, the political pluralism is seen as strength and is not stifled. Trade unions are well organized and constitute pressure means against the government. Benin is also the first country which organized the first national conference on the continent in 1990. Benin is moreover the pioneer in the establishment of an independent electoral commission. Benin is worthy  of note due the fact that this country didn’t stay paralyzed in a kind of excitement following this historical role of democratic precursor, but as the analyst Constantin Somé rightly underlines in his master’s thesis: « Benin distinguishes itself by its innovation ability in all fairness and transparency, which shows progress. Refusing the usurpation of political power by any group or faction that wouldn’t originate from the electoral body choice. This is why  an independent and autonomous « a mediator »  charged with elections has been established. Benin cultivates pacifism by an increasingly healthy management of electoral competitions and a progressive institutionalization of organs charged with regulating elections and above all their independence towards the government, the parliament and public authorities ». [1]

n

n Ghana takes second place in Africa behind Namibia and the 26th at the global level of 2016 Reporters without Borders (RSB) ranking about press freedom. [2] This prominent place in this international ranking conveys the steady challenge of guaranteeing press independence and freedom of speech and opinion prerogatives. On the political level, the popular vote is respected and the losers accept their defeat. During the presidential election of 2012, Dramani Mahama was declared the winner by the Constitutional Court against Akuffo Addo after recourse of the latter before the said court. Following this sentence, he admitted his defeat and called Mahama to congratulate him. In 2016, the outgoing president Mahama was defeated by Akuffo-Addo during the elections and admitted instantly his defeat. This gives every reason to believe that the Ghanaian democracy is constantly growing.

n

n Still in West Africa, Senegal is also an avant-garde in terms of democracy in our continent. Even if this country has known intermittent episodes of « crisis », it always knew how to recover. The longstanding and strong tradition of activism in the political, community and trade union spheres (Ex : Collectif Y’EN A MARRE, Raddho, Forum Civil as well as other organizations of the civil society and lively and committed political parties) forms a significant safeguard against authoritarian and anti-democratic vague desires. President Wade’s defeat against his opponent Macky Sall in 2012, the constitutional referendum organized in 2016, illustrate the healthy democratic condition of this country and the desire of citizens and political leaders to preserve the Senegalese democratic ethos. The insular States that are Cape Verde and Mauritius deserve as well to be mentioned as model democracies in the continent. These countries experience a political stability which is in particular the result of an institutionalization and of the respect of democratic rules and practices that govern the public action as well as the private sphere.

n

n In respect to South Africa, it is a democracy which works well generally. Unlike a lot of countries in our tropics, we can add to the credit of this nation that the judicial power is still independent from the executive one. As proof of this, we can quote the legal problems of president Zuma entangled in corruption and abuse of power scandals. We all recall the reports of the Republic ex mediator Thuli Madonsela who revealed in all independence –even if she suffered political pressures- the « Nkandlagate » which refers to the renovation of a private residence with public funds and also the case concerning the narrow collusion between Zuma and the wealthy Gupta family. Even if the targeted murders are plentiful in this country, we can still notice that on the institutional field, freedom of speech is guaranteed and respected, as shown by EEF (Economic freedom fighters),deputies’ severe grumblings of Julius Malema during parliamentary sessions in the presence of president Zuma.

n

n Sao Tomé and Principe is a democratic role model in Africa. Even if this little country, not much strategic in a geographical and economical perspective arouses little interest for the international observers and analysts, the essentials of democracy are established there and have value. The same analysis can be made for Tanzania.

n

n According to a 2014 Reporters Without Borders (RSB) rank about press freedom, Namibia is the only country in Africa to get a score more or less similar to Scandinavian countries’, performing better (19th at global level) than France (37th) and many more countries of the Old Continent. Namibia is also the first African country to organize presidential and legislative elections by electronic vote in November 2014.Botswana is also quite reputable for its democracy. This country organizes regularly free and transparent elections, has good results in respect of good governance and fight against corruption even if we cannot ignore the coercive and repressive measures taken against the San minority, also called Bushmen. In North Africa, Tunisia tries to stand out from his neighbours. Tunisia adopted a progressive constitution and organized in 2014, free and transparent elections. Trade union or civil society activism such as the UGTT (Tunisian general union of work) and the Human rights league in Tunisia (LTDH) has without a doubt been an essential contribution in this democratic burst.

n

n The political systems resistant to the long-term establishment of democratic principles

n

n Alongside these countries that show notable democratic profiles, there are countries that counteract the good effects and are  still hostages to authoritarian systems or insufficiently democratic. In Africa, many regimes establish “cosmetic” or facade democracies. Many regimes claim that they become infatuated with democracy fundamentals such as multi-party system, free and transparent elections, Rule of law and basic law, even though the running of their countries reflects clearly an arbitrary power, autocratic or/and corrupt…the choice is yours. The Great Lakes region of Africa (Uganda, DRC, Rwanda and Burundi) and countries such as Eritrea, Gambia, Zimbabwe, Sudan, Djibouti, Ethiopia, Egypt, to name but a few, are among many that are far from having achieved the advisable or desired standards of a democracy. It is clear that the democratic situation of these countries is not utterly uniform. Some of these countries are led by tyrannical and last-ditch regimes, frontally resistant to populations’ democratic ambitions. Whereas in other countries, despite serious democratic gaps, some basic democratic principles are relatively, sometimes according to the desires of the regime, well promoted and applied.

n

n African populations and especially the youth are very thirsty for democracy to freely express their potentials. They don’t want be stifled anymore by authoritarian obsolete drifts. Lately, we saw how Yahya Jammeh’s regime in Gambia attempted to carry out an illegitimate takeover in order to stay in power despite his defeat. This megalomania got fortunately what it deserved: a failure. The African Union as well as the sub regional organizations must assume an active role to stop the authoritarian momentums. It will be good when African democracy rises from the ashes and moves forward to progress!

n

n  

n

n [1] Somé, Constantin (2009, pp.31-32): “Pluralisme socio-ethnique et démocratie : cas du Bénin », a dissertation made to achieve a Master in political science at Quebec University in Montreal.

n

n  

n

n [2] RSF rank: https://rsf.org/fr/classement

n

n Translated by

n

n Corinne Espartero

n

n  

n

FinTechs in Africa: Multifaceted Tools to Promote Financial Inclusion

n Mina lives in Sahuyé, 70 km away from Abidjan. Since 2008, she has used a mobile money account which she uses to send money to her aunt in Ouagadougou and to save a few bucks each month. Along with 100 million other people, Mina is now able to have access to basic financial services, which she did not have before. To what extent do FinTechs allow financial inclusion on the continent? Do they indeed offer financial services to all, from the Cape to Algier, from Dinga in Central African Republic and to Gondere in Ethiopia?. FinTechs are not a unique and global solution for Africa – it would be reductive to say that they are. They nevertheless offer a relevant response to daily challenges, as well as innovations that change profoundly the global financial ecosystem.
n

n
n

n

n The singular breakthrough of FinTechs in Africa
n

n
n

n Africa positions itself as new territory for financial services. Africa is one of, if not the only continent to have leaped directly to dematerialized financial services, without having to go neither through permanent agencies nor through large-scale landlines. This particularity can be explained through unpropitious access to the classic financial offer. Formal services are provided by agencies concentrated in urban areas, while the rural areas represent 2/3 of the African population and with high interest rates and commissions (around 10.07% in the ECOWAS region for example), one can then easily explain why people resort to inexpensive financial technologies.
n

n
n

n This has then promoted a wider financial inclusion by granting access to basic financial services to a larger number of people and to marginalized communities. While the percentage of unbanked populations is 66% in Africa, with noticeable differences between countries, A resort to FinTechs is bringing about major change with 12% of Africans being able to access to financial services via FinTechs.However, it is clear that mobile money is only a solution among many others that are available to solve the problem. There are also money transfers, banking services, investment and wealth management operations, etc. This diversity is reflected in the diversity of African markets themselves, of their maturity and their needs. If some options, especially mobile money, are indeed fruitful in one country they may not make sense in another where a more or less sophisticated option would be more useful. Furthermore, some countries' profiles facilitate the deployment of one solution, where elsewhere the same solution would only respond partially or even not at all to increasing access to financial services. M'Pesa's success in Kenya, based on a demand-driven solution, has not been duplicated in Tanzania or Nigeria. These failures are linked to the diversity of ecosystems, highlighting the importance of adopting a plural approach to financial inclusion.
n

n
n

n  
n

n
n

n Challenges to FinTechs face and Solutions
n

n
n

n Mobile Money today is the most developed and successful platform for financial inclusion in Africa. It positions itself as a gateway for a variety of services for its users. However, many issues must be solved to truly provide inclusive access, that is, financial service accessible to all, including those at the « bottom of the pyramid » Financial inclusion of people at the bottom of the pyramid remains indeed challenging, with or without FinTechs. This population, who live below the poverty line, carry out small operations, not above 2$ a day. Yet the agent-based model in the mobile banking system, whose revenue is 100% dependent on transactions, needs a certain total amount to become profitable. Considering 1$-operations conducted by an agent who spends monthly between 150 and 200$ and takes a percentage per transaction, the agent should register an amount of 20.000$ to get to the break-even point, which amounts to 2 transactions per minute, 8 hours a day, 7/7… Moreover, bragging about mobile penetration figures in Africa should not obliterate some realities. Mobile user rates in some African countries do not exceed 30% – on 100 people, only 30 in Burundi and 6 in Eritrea use a mobile phone. Digital data are also coming short. According to the telecoms company Tigo, only 20% of its clients / customers throughout the continent use data. Even if innovative financial services are multiplying, access to basic services is not yet guaranteed on the continent.
n

n
n

n Other challenges remain to be overcome in order to  increase FinTechs ‘ coverage and ensure equal access to all, such as interoperability, which hinders domestic and international money transfers and efforts regarding financial education and awareness. While Rwanda can be cited as an example in terms of financial education, other countries like Nigeria do not promote FinTechs culture. For example, the Rwandan government has supported the implementation of digital platforms for basic services (Irembo) : payment for electricity bills, administrative procedures, etc. On the contrary, the economy in Nigeria is mostly based on liquidity with street agents, called Esusu or Ajo, operating day-to-day informally.
n

n
n

n  
n

n
n

n FinTechs potential provide a visionary ambition for Africa
n

n
n

n If these limits / boundaries must be solved, the development of FinTechs paved the way for major progress towards financial inclusion. Financial inclusion is not limited to payments nonetheless. This « frugal innovation » deploys a wide range of financial services made accessible to most. Among the proposed services, there are of course the classic banking services, offering the possibility to those excluded from the banking system to take out a loan (as with Aire or Kreditech), insurance and micro insurance, investment, payment and online transfer services. Startups like Afrimarket, Azim or Mergims facilitate money or goods transfers safely at reduced rates. WeCashup and Dopay offer the possibility to pay online and/or get paid electronically, without any risk of corruption or security breach.
n

n
n

n Moreover, these services not only increase financial inclusion, but also increase social inclusion with products facilitating access to basic services in health and education. For example, the Senegalese FinTech Bouquet Santé relies on the diaspora to solve some deficiencies in the national health system.These initiatives are supported by a range of elements facilitating the deployment  of digital solutions. First, the simplicity of the technology most frequently used, the USSD, as well as the dynamism of this sector which constantly offers innovations improving this technology and new applications. Second, the low cost of mobile phones, which promotes an easy and increasing penetration. Third, the ability to set up an extended distribution network, even in rural areas, throughout an agent-based system for mobile money. Finally, the increasing trend for players to seize this opportunity and to develop partnerships (between operators, banks, cooperatives, microfinance institutions) and facilitate the growth of their services with an effort in training and raising awareness.
n

n
n

n So far, FinTechs have achieved a lot in increasing access to financial services. Today, the coverage of mobile money services in Africa exceeds 80%. In Kenya, access to banking services has increased by 58% since 2007, the year when the national unicorn M'Pesa was launched. It is undeniable that access to basic services has been reinforced on the continent with 15.4% of the total value of transactions in 2014 regarding bill payments and trade transactions.The growing access and participation in the financial system is not an end in itself, but a means to an end. They offer major direct and indirect advantages. At the heart of the system, they allow to reduce costs for trans-border funds transfers and for financial services by 80-90%, allowing companies to offer their services to low-income customers while securing their profitability. For users, they decrease the insecurity that goes with cash and provide the possibility to smooth their consumption, to manage risks linked to financial shocks by saving money, and step by step / little by little, to invest in education and health. For companies, facilitating access to credit by creating credit history allows them to grow and create jobs.
n

n
n

n Last but not least, the growing interoperability and openness promoted by African regional integration offer exciting perspectives. Beyond mobile money, the bitcoin and block chains are a work in progress in Africa; some dare say that they could bear a revolution, the Impala Revolution. The block chain, which allows for the establishment of credit history, to check and/or create a basic financial identity may even be the next innovative leverage for financial inclusion and a tool for Africa to pioneer FinTechs at global level. To conclude, the possibility of providing larger access to financial services implies proposing tailored solutions covering the full range of needs on the continent, even adopting a local perspective because what is true in the capital city is not true anymore in a village. As a result, it is key not to believe in a single model capable of solving Africa's challenges as a single and homogenous entity. Finally, the key issue is to maintain the entrepreneurial vitality that can be observed for now in the FinTech sector.
n

n
n

n Translated by:
n

n
n

n Manon Richert
n

n

n

The private sector: A strong vector for Morocco’s economic integration in Africa

n During the 27th African Union summit in Kigali of 18th July 2016,King Mohammed VI declared that ‘’Morocco is already the second investor in Africa but aims to become the Continent’s foremost investor very soon”. Indeed, between 2003 and 2013, more than 1.5 billion dollars have been invested by Moroccan companies in West and Central Africa. This only represents half of the direct foreign investments launched by Morocco, in the last few years.

n

n In the early 2000’s, many Moroccan companies of the private sector started businesses in Africa in a wide range of sectors. For example, bank branches of BCP (Banque Centrale Populaire), BMCE Bank of Africa and Attijariwafa Bank have been opened in about fifteen African countries. More so, the insurance company Saham has also been planted in about twenty countries since the takeover of the Nigerian company Continental Reinsurance in 2015.  In the telecommunications sector, Maroc Telecom increased its influence on the continent through the takeover of 6 African branches from their Emirati shareholder Etisalat.

n

n Moreover, many holdings such as Ynna Holding and the National Investment Company through its mining branch Managem, have operations in the African continent.  In the property business, the company named Alliances Développement Immobilier, has signed partnership agreements with the Cameroonian and Ivorian governments in order to build thousands of council housing. The company, Palmeraie Développement, has launched building projects in Gabon, Ivory coast and recently in Rwanda. Attracted by the important investments in infrastructure (highways, bridges, ports, council housings, universities, etc.), the Addoha group pitched its tent on the continent too via two of its companies: Addoha and CIMAF (Ciments de l’Afrique). They have been recently joined by LMHA (LafargeHolcim Maroc Afrique), a company held jointly by LafargeHolcim and the national investment company which is a Royal Holding.

n

n So, the private sector plays a key role in the economic integration process of the continent. The mobilization of private investments is essential to economic integration as it helps to create jobs, improve productivity and increase exports. The economic integration between Morocco and other African countries put in place by the King Mohammed VI invites the companies of the Kingdom to share their expertise and to strengthen their partnership relations with the African countries.

n

n The Moroccan private sector will now play an important role in skill transfer, while enhancing its production capacity. It will then improve its competitiveness on an international level. Concerning inter-regional trade, it will boost the commercial exchanges, which are still weak and reduce the structural deficit of the Moroccan trade balance. The economic potential is huge. The Economic Community Of West African States (ECOWAS) and The Economic Community of Central African States (ECCAS) have altogether more than 300 million consumers, that is to say a market which is  nine times the size of the Moroccan population.

n

n The Role of Economic-stimulus Groups in the Reinforcement of Economic bilateral relations

n

n Whenever King Mohammed VI makes an official visit to  a Sub-Saharan country, his country Morocco makes advantageous agreements that includes customs facilities and tax concessions. The aim is to promote commercial exchanges and to develop intra-African investments. Recently, economic relations between the Moroccan Kingdom and other African countries are ruled by a legal frame of more than 500 cooperative agreements. This is so important to the Moroccan Kingdom that the King Mohammed VI called a meeting of his government, during the first ambassador conference that took place in August 2013, to work with the different economic operators from the public and the private sectors in order to grab investment opportunities in countries having strong economic potentialities. Thus, the last trips of King Mohammed VI allowed mainly to create economic-stimulus groups on the between Morocco-Senegal and Ivory Coast. These groups, co-chaired by the foreign ministers and the presidents of employers of each country, aim to promote partnerships between the private sectors and to boost commercial trade and investments [1].

n

n With a total population of 22 million inhabitants, Ivory Coast is the first economy in the West African Economic and Monetary Union (UEMOA) area and is also the second economic power in the ECOWAS area. Also, the investment options are numerous: industry, infrastructure, construction industry, mines, energy, and so on. Senegal is also not left behind. There are so many reasons that encourage investment in the country. These include political stability, economic opportunities and new infrastructures. A guarantee is also given to the Moroccan investors through notably mutual protection and promotion agreements of investments and non-dual taxation agreements. The Memorandum of Understanding concerning the creation of a joint venture between the Moroccan group, La Voie Express and the Senegalese company Tex Courrier signed on 9th  November 2015 at the ceremony to present the work of the Moroccan-Senegalese EIG – chaired by King Mohammed VI and President Macky Sall, is a good example of the instrument's driving role in boosting private-private partnership[2].

n

n Exchanges between the Moroccan kingdom and the African continent have increased clearly during the last decade. Between 2004 and 2014, global exchanges have quadrupled, going from 1 billion dollars to 4.4 billion dollars. The study '' Structure of trade between Morocco and Africa: An analysis of trade specialization '' produced by OCP Policy Center in July 2016 shows that West Africa remains the first destination of Moroccan exports[3]. This region has indeed welcomed around 50.08% of exportations in 2014, the equivalent of 1.04 billion dollars[4]. However, an analysis of the export structure reveals that Moroccan exports to the other African countries are dominated by intensive goods in raw materials and natural resources[5]. A strong potential is to be developed to boost more Moroccan exports. The Directorate of Studies and Financial Forecasts (DEPF), attached to the Moroccan Ministry of Economy and Finance, stressed in its study "Morocco-Africa Relations: the ambition of a new border" that "Moroccan companies targeting the African market should focus on a penetration strategy based on cost considerations from targeted sectorial choices, in the light of the current and, above all, future needs of African populations. Demographic growth, the rise of the middle class and the rampant urbanization of the continent are all factors to be taken into consideration, in order to anticipate the rising configuration of these emerging economies ".

n

n In this sense, Moroccan exporter companies had better anticipate the dynamics of economic, social and cultural transformations that are on the horizon in Sub-Saharan Africa by setting up adaptation strategies in order to capture a higher market share and catch up their delay in this fast-growing region.

n

n Economic Action at the Heart of Morocco's Integration Strategy in Africa

n

n Economic integration is important for both Morocco and the African continent.  The recent trips of King Mohammed VI to Rwanda, Tanzania, Senegal, Ethiopia, Madagascar and Nigeria is designed to reinforce this notion. The Eastern part of Africa is the fastest growing region in Africa. Added to that, its economic potential  is still unexploited. If Morocco wants to reinforce its influence on the African continent, a number of options have to be investigated. First, the internationalization of Moroccan companies and their investment in African countries have to be encouraged by putting at their disposal a real database on the specificities and the potential of each economy. Second, export flows to African countries have to be fostered. Both public and private actors are involved in the promotion of Moroccan products. The new Moroccan agency for the development of Investment and Export, as well as the ASMEX (Moroccan Association of Exporters), will have to conduct trade missions to various African deposits and offer national companies the necessary support to develop their exports and / or carry out their development project in the continent. Finally, strengthening trade integration with the various African countries is important. The consumer market is growing with the emergence of a middle class more interested in manufactured goods with a high added value. The negotiation of advanced partnerships with ECOWAS and CEMAC, including the creation of free trade areas, is in turn an ideal gateway to this large market of more than 300 million people.

n

n In the era of globalization and fierce international competition, the growing interest of emerging countries towards the African continent is marked by rivalries: China, India, France, Japan or Germany have all unveiled their African ambitions. Facing this international context, Moroccan diplomacy is more ambitious and aggressive. King Mohammed VI declared at the opening of the Moroccan-Ivorian Forum the 24th of February 2014: "Diplomatic relations are at the heart of our interactions. But, thanks to the profound changes that the world is undergoing, their mechanisms, their scope and even their place in the architecture of international relations are forced to adapt to new realities.”

n

n In the wake of this , Morocco would win by organizing a Moroccan-African business summit. The latter would be a continuation of the Africa Action Summit and would focus on the economic development potential of the continent. The Summit would bring together governments, businesses, the public and private sectors, around the economic, social and human development of Africa. The challenge is to reaffirm the strategy of influence of Morocco on the continent.

n

n Translated by:

n

n Pape Djibril Diagne

n

n


n

n [1] Economic impetus groups include 10 sectors identified as priorities: banking-finance-insurance, agri-business-fisheries, property-infrastructure, tourism, renewable energy-energy, transport- Logistics, industry-distribution, digital economy, social and solidarity-craft economy, human capital-training and entrepreneurship

n

n [2] Christophe Sidiguitiebe, Four new agreements signed between Morocco and Senegal, Telquel.ma, 10.11.2016: www.telquel.ma/2016/11/10/quatre-nouveaux-accords-signes-maroc-senegal_1523082

n

n [3] Four of Africa's top five trading partners (Algeria, Mauritania, Senegal, Côte d'Ivoire and Nigeria) are part of West Africa.

n

n [4] With regard to imports, the weight of North Africa accounted for nearly all Moroccan imports, with a share of 82% in 2014 compared with 53% in 2004, mainly by importing natural gas, manufactured gas, petroleum and related products.

n

n [5] Moroccan exports consist mainly of food and living animals (25%), machinery and transport equipment (18.5%), chemicals and related products (18.1%), manufactured goods 15.9%) and mineral fuels, lubricants and related products (11.7%).

n

n  

n

The Iroko project: The Crowd lending Pioneer in West Africa

n The Iroko project is the first crowdlending platform in West Africa. The objective is to allow individuals to lend their savings directly to small and medium-sized companies in West Africa, for a fixed term and interest rate.

n

n The project:

n

n The project was created by two former students of Paris HEC (who graduated in June 2016), passionate about the dynamics and stakes that cross the African continent, especially West Africa.

n

n Their work is based on a threefold observation: in the coming decades, the creation of millions of jobs represents a major challenge of the region, but SME’s are the main levers of job creation. However, these companies often lack the necessary funds for their development. This is the famous “missing middle” or “missing link” of financing. Since September 2015, they have been working on the opportunity of crowdfunding for small and medium businesses from West Africa and they conducted a feasibility study in April/May 2016 in Senegal and Ivory Coast. This study led to partnerships notably with Cofina group and Lendopolis (KissKissBankBank Group).

n

n There were 3 objectives: to develop a legal operational model in the West Arican legal framework (there is no regulation on crowdlending in West Africa yet), to gauge the SMB and lender's interest in the service and to create strategic partnerships with local institutions. Then, they  presented and published their report (which is available on their website) and went back in October to start their activity.

n

n The aim of the pilot stage (october to march) is to realize the three first lendings of about 30 millions CFA francs each. The first collection will start after the first project presentation during the launching event in Dakar on November 15th. They also joined the Cofina Group business incubator in Dakar.

n

n Function and business model

n

n The pivot of their model is their partnerships with agencies that assist SME’s, such as the Entreprise Upgrading Office or the ADEPME in Senegal. Every small and medium business funded is supported and  tutored by these agencies for at least a year.  These provide quantitative and qualitative information on the companies they assist and act as trusted third parties. The applications transmitted by these agencies are then reviewed by the Iroko Project team, and for those selected, presented to the lender community. The needs of the projects funded, vary between 10 and 100 million CFA francs. If the needs are more substantial, they can be complemented with a traditional bank loan. Once the project is presented online, lenders choose individually if they want to contribute, depending on the quantitative and qualitative information available on the company and its team. They also decide the amount they want to lend: between 100 000 and 2 million CFA francs. During this phase, lenders have the possibility to exchange with the manager and ask questions about the company activity. Data on social and environmental impacts are also highlighted, following the setting up of credit are also highlighted. These include: number of jobs created, reduction in the use of fossil energy, impact on local products etc. Once the collection is completed, the credit is disbursed and the reimbursements start. The proposed remuneration to lenders equals the credit interest rate and is around 9 to 14% each year.

n

n The service proposes a complementary source of financing and a performing savings product, affordable for individuals. Once the credits have been set up, the Iroko project teams are in charge of following up the reimbursements and the possible recovery in partnership with the agencies. Concerning the default risk, as a last resort, it is supported by the lenders who are actually paid for the risk taken.

n

n The economic model relies on the amount drawn during the credit setup, incurred by the company at a rate of 4,5 % of the total credit amount.For the lenders, the service is free and joining the community is very simple. Iroko project is open to every resident having a bank account in CFA francs. The only documents required are an ID and and bank transfer information.

n

n Conclusion

n

n The goal is to create a dynamic network where lenders and borrowers coordinate their funds, competence and know-how to encourage the development of the West African economic structure. The team is aware that their service targets the West-African privileged part of the population who have a strong savings capacity.   Developing innovative and popular payments channels such as mobile money is a priority.  However, these solutions are still very expensive and very difficult to bear by the parties at stake (SMB, lenders, Iroko Project).

n

n Finally, the team hopes that their initiative helps the implementation of a specific regulation for crowd lending in this region. That is the reason why they discuss with the Senegalese authorities and the UEMOA zone to support the reflexion in that way.

n

n The official project launching is scheduled on November 15th 2016 in Dakar.

n

n You can contact the Iroko project team at contact@iroko-project or on Facebook and Twitter

n

n Translated by

n

n Anne-Sophie Cadet

n